The Securities and Exchange Commission issued an order on September 17, 2026, creating a temporary innovation exemption to facilitate on-chain trading of tokenized National Market System (NMS) stocks. The relief runs for a five-year term through September 17, 2031, allowing qualifying venues to operate under conditional exemptions from exchange registration under the Securities Exchange Act of 1934.
The order allows registered broker-dealers and alternative trading systems to trade tokenized shares on public blockchains without registering as national securities exchanges, according to Forkast News. The move establishes a structured venue layer for tokenized equity transactions following a surge to $15.6 billion in monthly tokenized equity volume in September 2026.
The Mechanics of the Innovation Exemption
The SEC innovation exemption establishes a regulatory sandbox that permits an unaffiliated company to tokenize a public company's listed equity without corporate involvement. Tokenized securities venues (TSVs) may then offer those digital shares for trading, subject to conditions that include mandatory volume caps and platform limits.
Trading may take place only across three public blockchains: Ethereum, Solana, and BNB Chain, Forkast News reported. The SEC explicitly identified these networks for the controlled trial rather than establishing an open-ended channel for digital equities.
To participate, a TSV must post a public notice at least 30 calendar days before launching operations and email the SEC within one business day of that publication. Platforms can implement access controls by restricting liquidity pools to allow-listed wallet addresses or by programming the tokenized stock itself to transfer solely among verified wallets.
Notice Windows and Issuer Objections
Public companies face a strict 30-day timeline once an unaffiliated firm seeks to tokenize their shares under the innovation exemption framework. A TSV must deliver a formal written notice to the company, giving the corporate issuer 30 calendar days from receipt to submit an objection before tokenized trading can start.
If a corporation does not object within the 30-day period, the firm is considered to have accepted third-party tokenized trading of its shares, Latham & Watkins LLP reported. If an objection is lodged, the venue must update its public notice within five business days to disclose the objecting issuer and contact the SEC by email within one business day.
A corporate objection halts that specific TSV from using the exemption for that issuer's NMS stock, yet it does not prevent third parties from tokenizing shares or stop competing TSVs from filing separate requests. Issuers that tokenize directly or authorize their own tokenization are entirely exempt from the issuer notice mandate.
Market Structure and Infrastructure Concerns
The framework generates distinct market structure questions because TSV activity bypasses the consolidated tape and is not routed to a securities information processor. TSV trading does not register in standard volume channels, meaning consolidated feeds might understate true market liquidity, trading turnover, and daily volume metrics.
Latham & Watkins LLP noted that while volume ceilings apply to each individual TSV, aggregate on-chain turnover could surpass those thresholds across multiple independent venues. Issuers are advised to coordinate with listing exchanges and transfer agents regarding how on-chain activity is measured, while checking with legal staff as notices arrive.
The framework covers all exchange-listed domestic stocks as well as foreign private issuers, exposing American Depositary Receipt issuers to dual-halt coordination risks. A TSV must halt trading when the primary US exchange halts, but foreign shares remain vulnerable to overnight trading discrepancies if overseas listing bourses freeze while US trading desks are closed.
Industry Reaction to the Innovation Exemption
The new rules coincide with proposed SEC modernization of transfer agent rules permitting distributed ledger tracking, according to Forkast News. Early institutional activity under the sandbox is anticipated to center on highly liquid, widely held equities as market participants evaluate the innovation exemption.
Corporate stakeholders have begun submitting formal input regarding the regulatory perimeter. FinTech Magazine reported that Bitcoin Bancorp, Inc. submitted a formal public comment asking the SEC to clearly distinguish pure infrastructure vendors from registered securities dealers.
Bitcoin Bancorp Executive Vice President Eric Noveshen stated that "Tokenization of stocks and real-world assets is gaining momentum within capital market structures and Bitcoin Bancorp’s letter to the SEC supports the proposition that certain digital-asset access providers should receive securities-law relief." Noveshen added that "A company that verifies identity, has full AML/KYC compliance, and facilitating trading of tokenized stocks should receive an exemption from the definition of a “dealer" under federal securities statutes.
Legal Status and Investor Rights
Under the regulatory order, eligible tokens must convey identical rights to the underlying stock. Venues are permitted to offer a tokenized NMS stock for trading only after verifying that holders receive full rights parity, specifically including proportional voting rights.
Holders of tokenized shares would generally be classified as beneficial owners of the stock rather than record owners on an issuer's master securityholder ledger, Latham & Watkins LLP reported. The tokenizing institution or an affiliated entity typically acts as the depository intermediary holding the underlying registered shares.
Companies pursuing direct tokenization gain greater oversight over their wrapper, trading venue, and disclosures. Meanwhile, issuers assessing third-party venue filings under the innovation exemption must review operations carefully, as unaddressed notices permanently open the door to on-chain trading.
Conclusion
The SEC innovation exemption establishes an active five-year test environment for trading tokenized NMS stocks on Ethereum, Solana, and BNB Chain. As the immediate exemption runs toward its September 17, 2031 expiration date, the SEC will collect trading and settlement data to decide whether to codify permanent rules or allow the relief to sunset.
Frequently Asked Questions
What is the duration of the SEC innovation exemption?
The SEC innovation exemption was issued on September 17, 2026, and provides a five-year temporary conditional relief period running until September 17, 2031, according to Latham & Watkins LLP and Forkast News.
Which blockchains qualify under the SEC order?
According to Forkast News, trading under the SEC exemption is restricted to three qualifying public distributed ledgers: Ethereum, Solana, and BNB Chain.
How long do public companies have to object to an Issuer Notice?
Corporate issuers have 30 calendar days from the date they receive an Issuer Notice to object; failing to act allows the tokenized securities venue to begin trading on day 31, according to Latham & Watkins LLP.
Do tokenized shares carry shareholder voting rights?
Yes. A tokenized securities venue may only list tokenized NMS stocks after confirming that token holders receive the same economic and voting rights as underlying shareholders, establishing them as beneficial owners under Rule 13d-3(a).
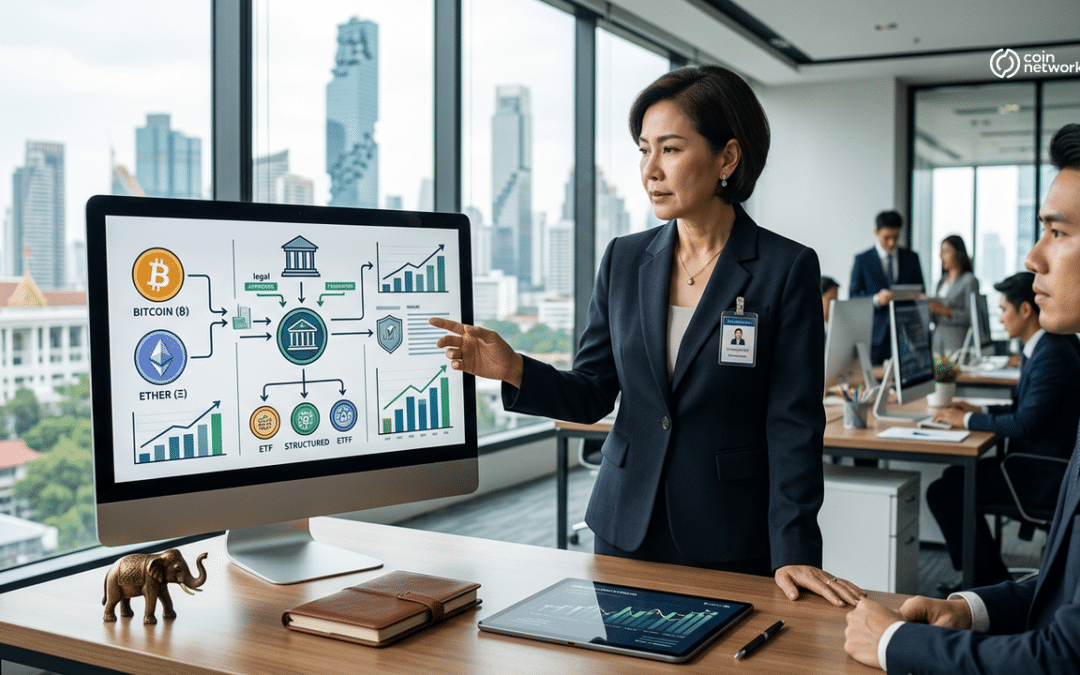
Thailand's Securities and Exchange Commission has finalized a regulatory framework allowing local fund managers to establish spot crypto ETFs, with the rules scheduled to take effect Oct. 16, 2026. Under the 11 notifications released by the regulator on Oct. 8, the framework permits products tracking bitcoin and ether to list and trade exclusively on the Stock Exchange of Thailand.
The framework establishes operational parameters for digital asset fund management, the appointment of qualified custodians, and investor protections across the domestic financial market. While the rulebook opens the door for fund sponsors to submit products for regulatory clearance, regulators noted that each individual investment vehicle must still secure dedicated SEC approval before public trading begins.
According to CryptoRank and local reports, the finalized measures set explicit operational expectations for any domestic asset management company planning to enter the space. Under the published structure, the scope of the market remains intentionally narrow during its debut window, anchoring initial permissions strictly to products tied to the two largest digital assets.
Custody Mandates and Exchange Exclusivity for Crypto ETFs
The finalized rules mandate that all underlying digital tokens held by the funds must be stored with digital asset custodians supervised directly by the Thai SEC. Fund managers will not have the option of listing on secondary domestic trading venues, as products are restricted entirely to the Stock Exchange of Thailand.
Crypto Briefing reported that the SEC announced its operational requirements on Oct. 16, 2026, setting baseline standards for asset management companies and mutual fund supervisors. The regulator also noted that it may evaluate the inclusion of qualified foreign digital asset custodians at a future stage if deemed suitable.
The rules outline detailed criteria covering technical infrastructure and organizational readiness before an institution can supervise custody pools for crypto ETFs. By centralizing holding verification with locally authorized entities, the commission intends to retain direct regulatory oversight over reserve balances and prevent offshore operational risks.
Institutional Allocation and Cross-Border Investment Limits
Alongside requirements for new offerings, the SEC updated its provisions to allow domestic mutual funds and private funds to invest directly in Thai-established crypto ETFs within their existing statutory investment boundaries. Previously, local funds were permitted to allocate capital only toward foreign-domiciled crypto products.
The commission has barred securities firms from offering margin loans to investors seeking to buy crypto ETFs, aiming to limit leverage risks. During the initial rollout, regulators have blocked retail access to cross-border crypto wrappers, prohibiting local brokerages from assisting general retail investors with foreign crypto ETFs while restricting such transactions strictly to institutional and ultra-high-net-worth clients.
Financial intermediaries are also barred from listing or distributing alternative instruments referencing offshore crypto products, including depositary receipts. The SEC confirmed that these restrictions will remain intact throughout the initial phase of implementation.
Consultation Process and Launch Requirements
The finalization of the 11 regulatory notifications follows a pair of public consultations conducted by the regulator earlier in the year. The SEC sought industry feedback regarding its core principles across April and May 2026, followed by a second consultation phase covering the detailed draft text throughout August and September.
Industry executives emphasized that Oct. 16 represents the legal activation of the regulatory regime rather than a confirmed debut date for live market trading. Fuwattananukul stated that commercial success will depend on structural execution, observing, "Whether these products draw meaningful investment will depend on a few things: competitive fees, tight tracking of the underlying asset, and investor education."
Addressing the behavioral hurdles facing traditional market participants, Fuwattananukul remarked, "For many investors, especially those wary of opening exchange accounts or managing wallets, ETFs through their existing brokerage accounts remove a real barrier." Chimphlapibul noted the significance of local execution, adding, "However, the actual outcome will depend on operator readiness and investor response."
Prospective fund promoters must prepare independent administrative paperwork, obtain clearance for individual product prospectuses, and coordinate with the SET prior to any public listing. The SEC emphasized that general regulatory permission does not waive standard scrutiny for new investment funds.
Investor Protection Rules for Crypto ETFs
Under the regulatory standards, brokers must provide comprehensive disclosures explaining the structural features and volatile characteristics of digital assets to prospective buyers. Securities firms are legally required to obtain explicit confirmation from clients verifying that they comprehend the risks before executing any purchase of crypto ETFs.
The debut of the ETF channel coincides with changing domestic participation trends. According to 99Bitcoins citing official SEC data, active trading accounts across Thai digital asset exchanges dropped to 121,000 in July 2026, marking a 21.82% slide from June and a sharp drop from roughly 265,000 active accounts documented in 2024.
The mandate for formal risk acknowledgments applies uniformly across all authorized brokerages distributing the vehicles. By barring margin facilities and enforcing mandatory disclosure checkpoints, the regulator seeks to curb reckless retail speculation while still establishing an accessible route to regulated digital asset exposure.
Conclusion
The Thai Securities and Exchange Commission's regulatory package establishes the formal legal foundation for spot bitcoin and ether funds to trade on the Stock Exchange of Thailand. With the 11 notifications taking effect on Oct. 16, 2026, the next concrete step requires local asset managers to prepare organizational infrastructure, submit fund applications for SEC review, and secure formal listing clearance before any products can launch.
Frequently Asked Questions
When do the Thailand SEC crypto ETF rules take effect?
The regulatory framework takes effect on Oct. 16, 2026. The Thai SEC released 11 notifications on Oct. 8 finalizing the legal guidelines for fund establishment, though individual products still require explicit regulatory clearance before listing.
Which digital assets are permitted under the framework?
The initial phase of the framework permits exchange-traded funds to track only bitcoin and ether. All qualifying funds must be listed and traded exclusively on the Stock Exchange of Thailand.
Are Thai retail investors allowed to purchase foreign crypto ETFs?
No. Under the SEC rules, Thai brokerages remain barred from facilitating investments in foreign crypto ETFs for retail clients. Offshore products are restricted exclusively to institutional and ultra-high-net-worth investors.
Can investors trade crypto ETFs using margin loans?
No. The SEC has explicitly prohibited securities firms and brokers from issuing margin loans to clients for purchasing crypto ETFs, keeping leverage curbs aligned with existing rules for direct digital asset acquisitions.
Restaking Slashing Risks arise when staked assets are used to secure additional services and can be penalized if the associated operator violates the rules of those services.
Traditional Ethereum staking already includes penalties and slashing for certain validator behaviors. Restaking adds another layer because the same economic stake can support additional applications or services.
EigenLayer describes restaking as a way to extend Ethereum’s cryptoeconomic security to additional applications through Actively Validated Services (AVSs) and operators. Its current documentation explains that the Slashing and Operator Sets upgrade gives AVSs the ability to slash stake when operators break defined service commitments.EigenLayer’s current overview of restaking and slashing provides the latest architecture.
This creates an important distinction:
Ethereum consensus slashing and restaking-related slashing are not necessarily the same event.
A validator can be exposed to the Ethereum protocol’s own penalties while also taking on additional economic commitments through a restaking system.
How Restaking Works
Restaking allows already-staked assets to be committed to additional services.
In EigenLayer’s model, participants can act as:
Restakers: Stake assets and opt into additional security arrangements
Operators: Run software for AVSs
AVSs: Services that use operators and economic security
EigenLayer’s current documentation states that restaking can involve native ETH, liquid staking tokens, EIGEN, and certain ERC-20 assets, depending on the configuration.EigenLayer’s restaking overview explains the available participation models.
The economic rationale is that new services do not necessarily need to build an entirely separate validator or security network from scratch.
The trade-off is that participants accept additional rules and therefore additional forms of operational and economic risk.
Restaking Slashing Risks vs Ethereum Slashing
Ethereum’s base protocol has its own slashing mechanism.
For a standard 32 ETH validator, Ethereum’s current documentation describes an initial penalty of 0.0078125 ETH, followed by a 36-day withdrawal period and a possible correlation penalty whose size depends partly on the total stake of validators slashed around the same period.
Restaking introduces a different question:
What happens if an operator breaks the rules of an additional service?
The answer depends on that service’s slashing conditions and the restaking architecture through which the stake was committed.
Therefore, simply saying that “restaking means you can lose your Ethereum stake” is too broad.
The exact exposure depends on the assets committed, the operator arrangement, the AVS rules, the applicable contracts, and the slashing mechanism.
Why Restaking Slashing Risks Exist
Restaking creates additional economic commitments because staked capital may secure more than Ethereum’s base consensus.
An AVS might require an operator to:
Produce correct responses
Execute a service honestly
Follow specific signing rules
Maintain uptime
Avoid conflicting messages
Provide verifiable computation
Validate external data correctly
The exact requirements vary by AVS.
If the operator fails to meet the service’s rules, the AVS may have a mechanism for applying penalties.
EigenLayer’s current documentation states that the Slashing and Operator Sets upgrade enables AVSs to slash stake when operators fail to meet defined commitments.The EigenLayer overview explains this framework.
Restaking Slashing Risks and Operator Behavior
Operators are particularly important because they run the software that performs an AVS’s tasks.
A restaker may delegate stake to an operator rather than operating the infrastructure directly.
This creates an additional layer of trust.
An operator may be exposed to:
Software bugs
Configuration mistakes
Infrastructure outages
Incorrect signing
Key-management failures
Misunderstanding of AVS requirements
Malicious behavior
EigenLayer’s documentation warns that restakers should carefully consider the reputation and legitimacy of operators, particularly where AVS governance or slashing functionality creates additional risk.EigenLayer’s restaking security guidance discusses these risks.
This means selecting an operator is not simply a performance decision. It can also be a risk-management decision.
Restaking Slashing Risks and AVS Rules
Not all AVSs carry the same slashing conditions.
One service may rely primarily on objective on-chain evidence.
Another may involve more complicated verification, external data, or application-specific rules.
That difference matters because a restaker should understand:
What behavior is considered a fault
Who can submit evidence
How evidence is verified
Who can trigger or approve slashing
How much stake can be affected
Whether penalties are burned or redistributed
What dispute or veto mechanisms exist
Whether the slashing process is upgradeable
EigenLayer has emphasized that slashing conditions and operator sets are intended to define economic commitments between AVSs and operators.
The specific conditions remain service-dependent rather than universal.
Restaking Slashing Risks and Correlated Failures
One of the most important concerns is concentration.
Suppose the same operator participates in several AVSs.
If that operator experiences a software bug or infrastructure failure affecting multiple services, the same economic stake could potentially be exposed across several commitments.
This is sometimes described as correlated risk.
It does not mean every failure automatically results in several penalties. The actual outcome depends on the rules and whether each AVS identifies a separate slashable offense.
However, the possibility of multiple commitments makes operational isolation important.
Operators may therefore need:
Separate infrastructure
Strong key management
Multiple client implementations where appropriate
Monitoring systems
Independent validation
Careful AVS selection
The broader EigenLayer risk discussion has long identified correlated failure and unintended slashing as important design considerations. TheEigenLayer whitepaper discusses these risks in its security framework.
Restaking Slashing Risks and Smart Contracts
Restaking systems depend heavily on smart contracts.
That introduces a separate class of risk.
Even when an operator behaves correctly, vulnerabilities in:
Restaking contracts
AVS contracts
Slashing modules
Operator-set configurations
Permission systems
Upgrade mechanisms
could potentially affect funds.
This means restaking risk is not limited to validator behavior.
A comprehensive assessment should consider both economic rules and software implementation.
For broader smart-contract security education, Coin Network’sCryptopedia provides related blockchain resources.
Restaking Slashing Risks and Native Restaking
Native restaking involves changing an Ethereum validator’s withdrawal credentials so that the relevant stake can participate in a restaking system.
EigenLayer’s current documentation explains that native restaking requires operating an Ethereum validator and changing its withdrawal credentials to EigenLayer smart contracts.EigenLayer’s native restaking overview describes the architecture.
This can create a different operational profile from liquid restaking.
The validator operator has direct responsibility for the infrastructure, keys, and service commitments.
As a result, operational mistakes can become more important.
Restaking Slashing Risks and Liquid Restaking
Liquid restaking uses liquid representations of staked assets.
These tokens can make staked capital easier to use elsewhere, but they add additional layers of protocol and smart-contract exposure.
An issue at one layer does not automatically trigger a slashing event, but it can affect liquidity, redemption, valuation, or user access.
Therefore, restakers should distinguish between:
Slashing risk
Smart-contract risk
Liquidity risk
Custody or operator risk
Depeg risk
Governance risk
These risks can interact without being identical.
Restaking Slashing Risks and 2026 Market Scale
Restaking remains a significant part of the 2026 DeFi landscape.
A current DeFiLlama snapshot records approximately $10.96 billion in total value locked across restaking protocols. EigenCloud accounts for about $7.13 billion, while Babylon holds roughly $3.51 billion in the same dataset.DeFiLlama’s restaking dashboard provides continuously updated protocol-level figures.
For Ethereum specifically, the current DeFiLlama snapshot reports approximately $6.98 billion in restaking TVL, with EigenCloud representing about $6.97 billion.DeFiLlama’s Ethereum restaking dashboard provides the current figures.
These are TVL measurements, not direct measures of the amount at risk of being slashed.
They also do not imply that all deposited assets are subject to identical slashing rules.
The distinction is important because restaking TVL can include different assets, configurations, operators, and service relationships.
Ethereum Staking Scale and the Size of the Security Base
Restaking builds on top of Ethereum’s proof-of-stake economy.
Ethereum’s validator infrastructure remains substantial, with tens of millions of ETH participating in staking according to current network dashboards such asBeaconcha.in.
The size of the underlying staking base helps explain why restaking can provide substantial economic security to additional services.
It also explains why governance and risk controls matter.
When large amounts of economic security become connected to additional applications, a failure in one component can potentially have consequences beyond that component.
The goal of restaking is therefore not simply to maximize the amount of capital securing AVSs. It is also to structure commitments so that the security gained is not outweighed by excessive correlated or technical risk.
How Restaking Protocols Reduce Slashing Risks
Several safeguards can reduce exposure.
Clear Slashing Conditions
AVSs should clearly define what constitutes a slashable offense.
Narrow Operator Permissions
Operators should only receive the permissions necessary to perform their duties.
Audits
Smart contracts and AVS software should undergo appropriate security review.
Monitoring
Operators can use automated systems to detect signing errors, downtime, and unexpected behavior.
Key Management
Validator and operator keys should be protected against unauthorized access.
Risk Diversification
Stakers can avoid concentrating their capital with one operator or one set of services.
Governance Controls
The process for submitting, verifying, disputing, or vetoing slashing decisions should be clearly documented.
EigenLayer’s documentation emphasizes that AVS governance and slashing functionality are security-sensitive parts of the system.EigenLayer’s current restaking security documentation discusses these considerations.
What Can Trigger Restaking Slashing?
The exact trigger depends on the AVS.
Potential categories include:
Signing conflicting messages
Incorrect service results
Deliberate invalid behavior
Failure to meet objective service requirements
Violating an AVS-specific commitment
Operator actions that create a provable fault
Not every uptime failure is necessarily slashable.
Not every software bug automatically results in a penalty.
The actual conditions must be defined by the relevant service and slashing implementation.
This is why restakers should read an AVS’s documentation before delegating to an operator.
How Restakers Can Evaluate Slashing Exposure
Before participating in restaking, review:
Asset
What asset is being committed?
Operator
Who will perform the service?
AVS
Which services will receive security?
Rules
What actions are considered slashable?
Maximum Exposure
How much stake can potentially be affected?
Governance
Who controls slashing decisions?
Evidence
How is a violation demonstrated?
Software
Has the relevant code been reviewed?
Diversification
Is the stake concentrated in one operator or AVS?
Withdrawal
What are the withdrawal and exit conditions?
Coin Network’sDeFi resources can provide broader context for evaluating smart-contract, liquidity, and protocol risks alongside staking-specific research.
Common Mistakes About Restaking Slashing Risks
Assuming Restaking Automatically Slashes Ethereum
Restaking does not mean every AVS violation automatically triggers Ethereum’s native consensus-slashing mechanism. The relevant penalty depends on the architecture and rules involved.
Assuming More Yield Means Better Risk-Adjusted Returns
Additional rewards may compensate for taking additional risk, but the relationship depends on the probability and severity of adverse events.
Looking Only at the Operator
AVS design, contracts, governance, and slashing implementation also matter.
Ignoring Correlated Risk
Using the same operator across multiple services can increase concentration of operational dependencies.
Treating Audits as Guarantees
Audits reduce some software risks but cannot eliminate all technical, economic, governance, or operational risks.
Restaking Slashing Risks: Practical Checklist
Before restaking, check:
Asset: What exactly is being restaked?
Operator: Who runs the infrastructure?
AVS: Which services use the stake?
Rules: What behavior can trigger penalties?
Penalty: How much stake can be affected?
Evidence: How is a violation proven?
Governance: Who controls slashing?
Contracts: Which smart contracts enforce the system?
Audits: Has the code received appropriate review?
Concentration: Are several services dependent on the same operator?
Monitoring: How are faults detected?
Exit: How can users withdraw or undelegate?
Liquidity: Could the restaked asset become difficult to exit?
Conclusion
Restaking Slashing Risks arise because restaking connects already-staked economic value to additional services and their own rules.
The opportunity is that AVSs can potentially obtain security from an existing Ethereum staking base rather than creating an entirely separate security network.
The trade-off is additional complexity.
Validators and restakers may face risks related to operator behavior, AVS-specific rules, smart contracts, governance, correlated failures, key management, and technical implementation.
Ethereum’s native slashing system remains separate from many restaking-specific penalty mechanisms. A validator can therefore have one set of Ethereum consensus obligations and additional commitments through a restaking protocol.
Current 2026 data also shows that the sector is material in size, with nearly $11 billion in TVL across restaking protocols in DeFiLlama’s current snapshot.
That scale makes risk management increasingly important.
The right question is not simply:
“How much reward does restaking offer?”
It is:
“What additional commitments am I accepting, what can trigger a penalty, and how much of my stake could be exposed?”
FAQs
1. What are Restaking Slashing Risks?
Restaking Slashing Risks are the risks that staked assets can be penalized when a validator or operator violates the rules of an additional service secured through restaking.
2. Is restaking slashing the same as Ethereum slashing?
No.
Ethereum has its own consensus-level slashing rules. Restaking can introduce additional, service-specific penalty mechanisms.
3. What can cause Ethereum’s native validator to be slashed?
Ethereum’s official documentation identifies offenses including signing conflicting blocks, surround voting, and double voting.
4. What can trigger restaking-specific slashing?
The trigger depends on the AVS or service.
It can involve incorrect service behavior, conflicting commitments, provable invalid activity, or other conditions defined by the service’s slashing rules.
5. Can restaking cause a validator to lose all 32 ETH?
There is no universal answer.
Ethereum’s native slashing rules and restaking-specific penalty systems are different. The maximum loss depends on the particular mechanism, validator state, asset configuration, and applicable rules.
Claims that every AVS can automatically confiscate an entire Ethereum validator balance are therefore too broad without examining the specific implementation.
6. What is an AVS?
An Actively Validated Service, or AVS, is a service that uses operators and economic security to provide verifiable functionality.
EigenLayer’s current architecture uses AVSs as a central part of its restaking model.
7. What is an operator in restaking?
An operator runs the infrastructure or software required by an AVS.
Restakers can delegate stake to operators, meaning operator selection can affect the risk profile of the restaked position.
8. Can an operator mistake cause slashing?
Potentially.
If the mistake produces behavior that meets an AVS’s defined slashable conditions, a penalty may be possible.
Whether downtime, configuration errors, or other mistakes are slashable depends on the specific service.
9. Is liquid restaking safer than native restaking?
Neither should automatically be classified as safer.
They involve different combinations of operator, liquidity, smart-contract, custody, and protocol risks.
10. What is correlated slashing risk?
Correlated risk occurs when the same operator, infrastructure, or dependency is exposed across multiple services.
A common failure can therefore affect multiple commitments at the same time, depending on the system’s rules.
11. How large is the restaking market in 2026?
A current DeFiLlama snapshot places total restaking TVL at approximately $10.96 billion, with around $6.98 billion on Ethereum.
TVL is not the same as slashable stake, so these figures should not be interpreted as the amount that could be lost through slashing.
12. Where can I learn more about Restaking Slashing Risks?
Layer 2 Sequencer Risks begin with the role that sequencers play in many Ethereum rollups.
A sequencer is a component responsible for receiving Layer 2 transactions, ordering them, and helping produce L2 blocks. In several major rollups, a centralized or relatively small sequencer set currently handles this work.
Arbitrum’s documentation explains that its sequencer is a specially designated full node with authority over transaction ordering. This allows users to receive transaction results quickly without waiting for Ethereum block production. The same documentation explains that non-sequencer transactions can enter a delayed queue on Ethereum when the normal sequencer path is unavailable.Arbitrum’s explanation of the sequencer provides the technical background.
This design improves the user experience, but it also creates an important operational dependency.
If the sequencer stops producing blocks, normal transaction processing can be interrupted even when Ethereum itself continues operating normally.
Why Layer 2 Sequencer Risks Matter
A sequencer can affect several parts of an L2 user experience.
During normal operation, users send transactions to the rollup’s sequencer, which orders and processes them quickly.
During a failure, users may experience:
Pending transactions
Delayed confirmations
Failed RPC requests
Stale application interfaces
Difficulty executing swaps
Delayed withdrawals
Temporary inability to interact normally with dApps
The exact impact depends on the rollup’s architecture and the fallback mechanisms available.
This is why sequencer availability is treated separately from the underlying security of Ethereum. A rollup may retain a strong settlement relationship with Ethereum while still having an operational dependency on its sequencer.
L2BEAT currently tracks 22 rollups and reports about $34.84 billion in total value secured across rollups. Its current risk framework separately evaluates sequencer failure, showing why sequencer availability is treated as a distinct architectural consideration.L2BEAT’s rollup overview provides the current ecosystem data and risk classifications.
Layer 2 Sequencer Risks During a Downtime
A sequencer outage does not necessarily mean that user funds are immediately lost.
The first and most common effect is usually a liveness problem.
The L2 may stop producing new blocks or stop accepting transactions through its normal RPC endpoint.
Applications may continue displaying the previous state, making balances or positions appear unchanged even though Ethereum itself remains operational.
This distinction is important.
A sequencer outage can affect the ability to act without necessarily compromising the correctness of previously finalized state.
Some rollups also maintain an L1 escape route that allows users to submit transactions without relying on the sequencer. The design and delay differ between networks.
A Real 2026 Example: Base Sequencer Block Production Outage
Base provides a useful recent example of why Layer 2 Sequencer Risks are an operational issue rather than merely a theoretical concern.
According to Base’s June 2026 postmortem, Base experienced two block-production outages on June 25 and June 26, 2026.
The first outage lasted 116 minutes, while the second lasted 20 minutes.
Base said the incidents were caused by a bug in sequencer block-building logic involving stale journal state after a transaction validation failure. The resulting invalid state transition caused the chain to halt.
During the incidents:
New L2 blocks stopped being produced.
Transactions waiting in the mempool were not included on-chain.
The transaction pool eventually became too large to store all pending transactions.
Some eth_sendRawTransaction requests returned errors.
Base reported that funds were safe and chain integrity was not compromised. The issue was mitigated by patching the sequencer logic.Base’s June 2026 incident postmortem provides the detailed timeline and root-cause analysis.
This example demonstrates an important distinction: sequencer downtime can disrupt transactions and application functionality without necessarily resulting in a loss of funds.
What Happens to Pending Transactions?
When a sequencer is offline, transactions submitted through the normal L2 route may remain pending or fail to enter the chain.
The exact behavior depends on the network.
On Base, for example, the June 2026 outage caused new transactions to remain unconfirmed because block production had stopped.
Other rollups may continue accepting transactions into a queue even when normal sequencing is unavailable.
For users, the practical lesson is that a wallet showing pending does not necessarily mean the transaction has been accepted into an L2 block.
It is useful to check:
The L2 status page
Block explorer activity
Transaction status
Sequencer health
Ethereum L1 activity
Official incident announcements
Layer 2 Sequencer Risks and Transaction Ordering
Sequencers do more than simply process transactions. They also determine transaction order within the permissions of the rollup’s transaction-ordering system.
This introduces another category of Layer 2 Sequencer Risks.
A centralized sequencer may have greater visibility into pending transactions than ordinary users. Depending on its architecture and policies, that can create opportunities for transaction reordering or MEV extraction.
L2BEAT explicitly identifies potential MEV extraction as a risk for systems where an operator can exploit its centralized position to influence transaction ordering.
For example, L2BEAT’s current risk analysis for OP Mainnet notes the possibility of MEV extraction if the operator exploits its centralized position and frontruns user transactions.L2BEAT’s OP Mainnet risk analysis provides the current assessment.
This does not mean every sequencer is actively exploiting users. It means the architectural position can create additional power that researchers should understand.
Sequencer Downtime vs Censorship
Downtime and censorship are related but different.
Downtime
The sequencer is unavailable or unable to produce new blocks.
Censorship
The sequencer is operating but intentionally or systematically refuses to include specific transactions.
A resilient rollup should ideally have mechanisms that allow users to bypass the sequencer if it becomes unavailable or misbehaves.
Arbitrum’s delayed-inbox design is one example. Its documentation explains that users can submit messages through Ethereum’s Delayed Inbox, and after the applicable delay, transactions can be force-included without relying on the sequencer.Arbitrum’s force-inclusion documentation explains this censorship-resistance path.
The current Arbitrum One design uses a maximum delay of approximately 24 hours before a delayed message can be force-included.
This means sequencer failure does not necessarily create an indefinite ability to block users, but it can create a significant delay.
How Rollups Reduce Layer 2 Sequencer Risks
Rollups can use several mechanisms to reduce sequencer dependency.
Forced Inclusion
Users can send transactions through Ethereum to bypass the normal sequencer.
Delayed Queues
Transactions can remain in an L1-managed queue until the sequencer processes them or the force-inclusion threshold is reached.
Multiple Sequencers
A decentralized or shared sequencer arrangement can reduce reliance on one operator.
Self-Sequencing
Some rollup designs allow users or external operators to participate in block production under certain conditions.
Escape Hatches
Smart-contract mechanisms can allow users to recover assets or execute important actions during sequencer failures.
The specific implementation matters more than the label.
A project describing itself as “decentralized” does not automatically mean that sequencing is fully decentralized.
Layer 2 Sequencer Risks and Withdrawals
Withdrawals are particularly important during downtime because users may need to move assets from an L2 back to Ethereum.
A sequencer outage can make the normal user interface unavailable, but well-designed rollups can maintain L1 pathways for important messages.
The exact withdrawal experience depends on the rollup.
Some systems allow forced L2 inclusion through L1. Others may have specific escape mechanisms or emergency procedures.
Users should therefore check a rollup’s documented exit path before assuming that a sequencer outage makes funds inaccessible permanently.
For broader Ethereum scaling research, Coin Network’sEthereum coverage andDeFi resources can be used alongside individual rollup documentation.
Layer 2 Sequencer Risks and Decentralization
Sequencer decentralization is still an evolving area.
L2BEAT currently classifies Base and Arbitrum One as Stage 1 rollups, while its framework explains that Stage 2 requires stronger decentralization and permissionless fraud-proof or validity-proof mechanisms along with tighter restrictions on emergency intervention and upgrades.
L2BEAT also emphasizes that its stages measure decentralization maturity rather than providing a complete security rating.Its Stages Framework explains the difference.
This distinction matters because a rollup can reduce sequencer-related trust assumptions while still having other technical or governance risks.
Users should therefore avoid interpreting a stage number as a simple “safe” or “unsafe” label.
The scale of the L2 ecosystem makes sequencer reliability increasingly important.
L2BEAT’s current data shows approximately:
$34.84 billion secured across rollups
$16.52 billion secured on Base
$11.51 billion secured on Arbitrum One
$2.01 billion secured on OP Mainnet
These values change continuously with asset prices and deposits, so they should be treated as current snapshots rather than fixed totals.L2BEAT’s value-secured dashboard provides the live figures.
As more capital and activity move to L2 networks, an outage can have wider implications for traders, DeFi applications, bridges, and market-making systems.
That does not mean a sequencer outage automatically threatens all assets on the network. It means the ability to process transactions efficiently becomes an increasingly important infrastructure requirement.
What Users Should Do During Sequencer Downtime
If an L2 appears to be experiencing an outage:
Check the Official Status
Confirm that the problem is actually network-wide rather than an issue with your RPC provider.
Avoid Repeated Resubmissions
Submitting the same transaction repeatedly can create confusion once sequencing resumes.
Check the Explorer
Determine whether new L2 blocks are being produced.
Review L1 Escape Options
Read the official documentation for forced inclusion, delayed queues, or other fallback mechanisms.
Be Careful With Time-Sensitive Trades
During an outage, applications may display stale prices or stale positions. Executing a trade immediately after recovery can also expose users to a changed market state.
Wait for Official Confirmation
A healthy RPC response alone does not necessarily prove that the network has fully recovered.
Common Misunderstandings About Layer 2 Sequencer Risks
A Sequencer Failure Means Funds Are Lost
Not necessarily. Sequencer failures primarily create liveness and availability issues, although the consequences depend on the rollup’s architecture.
Ethereum Is Down When an L2 Is Down
Not necessarily. An L2 sequencer can fail while Ethereum Mainnet continues to operate normally.
Every L2 Has the Same Backup Mechanism
No. Force-inclusion, delayed queues, self-sequencing, and escape hatches differ between networks.
Decentralized Sequencing Solves Every L2 Risk
No. It can reduce one class of dependency, but rollups still have smart-contract, bridge, proof-system, governance, and data-availability risks.
Stage 2 Means the Rollup Is Completely Safe
L2BEAT explicitly states that its stages measure decentralization maturity and should not be treated as a complete security rating.
Layer 2 Sequencer Risks: Practical Checklist
Before using a major L2, check:
Sequencer model: Who operates it?
Status: Is the sequencer currently healthy?
Fallback: Can users bypass it?
Force inclusion: What is the waiting period?
Censorship resistance: Can a transaction eventually be included without sequencer cooperation?
Withdrawal path: What happens during an outage?
MEV: What ordering powers does the sequencer have?
Decentralization: Is sequencing centralized or distributed?
Emergency controls: Who can intervene?
Upgradeability: Who can change the rollup contracts?
Data availability: Where is transaction data published?
Recovery: What happened during previous incidents?
For additional blockchain explainers, Coin Network’sCryptopedia resources can complement the individual rollup documentation.
Conclusion
Layer 2 Sequencer Risks are primarily associated with transaction availability, ordering, censorship resistance, and operational dependency.
A sequencer outage can stop new L2 blocks, leave transactions pending, disrupt DeFi applications, and make normal trading difficult even while Ethereum Mainnet continues functioning.
The June 2026 Base outages provide a recent real-world example. Base experienced a 116-minute outage followed by a 20-minute outage, during which L2 block production stopped and new transactions could not be included normally. Base reported that the incidents did not compromise chain integrity or user funds.
The severity of a sequencer failure ultimately depends on the rollup’s fallback architecture.
Systems with delayed queues and forced inclusion can provide users with a route around a failed or censoring sequencer, although those paths may involve significant delays.
As the Ethereum L2 ecosystem secures tens of billions of dollars, sequencer resilience is becoming an increasingly important part of rollup design.
The key questions for users and developers are:
Who controls the sequencer, what happens if it fails, and can users still force important transactions through Ethereum?
FAQs
1. What are Layer 2 Sequencer Risks?
Layer 2 Sequencer Risks are risks created by dependence on a sequencer to order and process L2 transactions.
They can include downtime, transaction delays, censorship, ordering risks, and operational dependency.
2. What happens when an L2 sequencer goes down?
Depending on the rollup, new L2 blocks may stop, transactions can remain pending, RPC requests may fail, and dApps may become difficult or impossible to use normally.
3. Does sequencer downtime mean my funds are lost?
No, not automatically.
A sequencer outage is generally a liveness or availability problem. Whether users can still move or withdraw funds depends on the rollup’s fallback mechanisms.
4. Can users bypass a sequencer?
Some rollups provide a mechanism for doing so.
Arbitrum, for example, uses a Delayed Inbox and supports force inclusion after the applicable delay. Itsofficial documentation explains the process.
5. How long can an Arbitrum transaction wait during sequencer downtime?
For Arbitrum One, the current maximum delay before force inclusion through the delayed path is approximately 24 hours.
The normal sequencer typically processes delayed messages much sooner, but the fallback mechanism exists for prolonged failures or censorship.
6. What happened during the 2026 Base sequencer outage?
Base experienced two block-production outages on June 25 and June 26, 2026.
The first lasted 116 minutes and the second 20 minutes. Base attributed them to a bug in sequencer block-building logic and said chain integrity and user funds were not compromised.
7. Can a sequencer censor transactions?
Potentially.
A centralized sequencer can have the ability to delay or exclude transactions from its normal sequencing path. The effect and available remedies depend on the rollup’s design.
8. Can sequencers extract MEV?
A sequencer’s control over transaction ordering can create opportunities for MEV extraction.
L2BEAT identifies this as a potential risk for some rollup architectures where a centralized operator has significant ordering power.
9. Are Base and Arbitrum fully decentralized sequencers?
Not currently in the strict sense used by L2BEAT’s decentralization framework.
L2BEAT currently classifies both Base and Arbitrum One as Stage 1 rollups, while its Stage 2 framework requires additional decentralization and trust-minimization properties.
10. Does Ethereum continue working during an L2 outage?
Usually, yes.
An L2 sequencer can experience an operational failure while Ethereum Mainnet continues producing blocks normally.
This is one reason L2 architecture includes mechanisms that use Ethereum as the settlement and fallback layer.
11. What should I do during a sequencer outage?
Check the official status page, avoid repeated transaction submissions, inspect the L2 explorer, review official fallback procedures, and be cautious with time-sensitive trades until normal sequencing resumes.
12. Where can I learn more about Layer 2 Sequencer Risks?
Ethereum Blob Fees are the fees paid for including temporary data blobs in Ethereum transactions. They were introduced through EIP-4844, also known as Proto-Danksharding, as part of the Dencun upgrade in March 2024.
Blobs provide Layer 2 rollups with a dedicated way to publish transaction data to Ethereum without using the traditional calldata pricing model. Ethereum’sofficial EIP-4844 specification describes blob gas as a separate fee market with its own base fee.
This distinction matters because Ethereum has two different resource markets involved in these transactions:
Regular execution gas
Blob gas
The price of one does not directly determine the price of the other.
For Layer 2 users, this creates a potentially important cost-saving mechanism because rollups can batch transactions and publish compressed data through blobs.
What Is Proto-Danksharding?
Proto-Danksharding is the first major stage of Ethereum’s longer-term danksharding roadmap.
Ethereum’sDanksharding roadmap explains that Proto-Danksharding adds data blobs to Ethereum blocks, giving rollups a cheaper way to publish data.
The term can sound complicated, but the basic idea is relatively straightforward.
A Layer 2 processes many transactions away from Ethereum Mainnet. It then needs to publish sufficient information back to Ethereum so that the rollup’s state can be independently verified.
Before blobs, rollups relied heavily on calldata for this data publication.
With EIP-4844, rollups can use dedicated blob space instead.
This does not mean blobs are permanent storage. Ethereum documentation states that blobs are intended to remain available for roughly 18 days, after which they can be pruned from ordinary clients. Long-term archival availability is a separate concern.
How Ethereum Blob Fees Work
The blob fee market is similar in concept to Ethereum’s EIP-1559 execution-fee market, but it operates separately.
EIP-4844 introduced:
Blob gas
A blob base fee
A target amount of blob space
A maximum amount of blob space
An excess blob gas value used to adjust pricing
The protocol calculates the blob base fee according to blob-space demand.
When blob usage exceeds the target, excess blob gas accumulates and the blob base fee can rise.
This means Ethereum Blob Fees are driven primarily by demand for blob space rather than by the computational complexity of ordinary smart-contract execution.
Ethereum Blob Fees vs Normal Gas Fees
One of the easiest mistakes is treating blob fees and normal Ethereum gas fees as the same thing.
They are not.
A normal Ethereum execution fee is associated with computation and other execution-layer resources.
A blob fee is associated with data availability space.
A rollup transaction can therefore be affected by both.
This separation allows the blob market to respond specifically to demand for Layer 2 data availability.
How Ethereum Blob Fees Affect L2 Costs
Layer 2 users typically do not pay the raw Ethereum blob fee as a separate line item.
Instead, rollup operators incur costs for publishing data to Ethereum and generally incorporate those costs into the L2 fee structure.
For optimistic rollups, Ethereum identifies several components of user fees, including L1 data publication, blob gas, and L2 operator costs.Ethereum’s optimistic-rollup documentation explains how these components work together.
For ZK-rollups, fees can also include data publication, L2 operator costs, and proof-related expenses.Ethereum’s ZK-rollup documentation describes these components.
This means lower Ethereum Blob Fees can reduce one important cost faced by rollups, but they do not automatically make every L2 transaction free or equally cheap.
Why Blobs Are Cheaper Than Calldata
Calldata and blobs both allow rollups to publish information to Ethereum, but they have different pricing and storage characteristics.
Calldata remains part of Ethereum’s permanent historical data and is priced through regular execution gas.
Blobs are temporary data objects with a dedicated fee market.
Ethereum’s documentation explains that blobs were designed specifically for rollup data and are generally cheaper than calldata for this use case. The data remains available during the protocol’s required serving window, while longer-term access can be handled by archival systems.
The difference is therefore not simply that blobs are “cheap storage.”
They are better understood as temporary data availability infrastructure designed for rollups.
Ethereum Blob Fees and Data Availability
Data availability is essential to rollup security.
A rollup publishes data to Ethereum so independent participants can reconstruct and verify the rollup’s state.
This is one reason blob fees matter beyond simple transaction pricing.
The goal is not merely to reduce costs. Ethereum needs a scalable way for rollups to make relevant data available without overwhelming node operators.
Proto-Danksharding therefore attempts to balance:
Rollup data availability
Network capacity
Node-resource requirements
L2 affordability
Ethereum security
Ethereum Blob Fees and Blob Capacity in 2026
The blob system has expanded significantly since EIP-4844 first launched.
The original Dencun configuration targeted 3 blobs per block and allowed a maximum of 6 blobs.
Ethereum later increased these limits through subsequent upgrades.
Following Fusaka and its Blob Parameter Only upgrades, Ethereum reached a target of 14 blobs per block and a maximum of 21 blobs per block in January 2026.
Ethereum’s January 2026 protocol checkpoint described this as a 2.3× increase in L2 data space compared with the pre-Fusaka configuration. The canonicalBPO2 specification records the 14-target and 21-maximum configuration.
This is important for L2 economics because more available blob space can reduce the likelihood that rollups compete for a severely constrained data-availability resource.
However, greater capacity does not guarantee permanently low blob fees.
If demand increases faster than capacity, blob prices can rise again.
Current 2026 Ethereum Blob Fee Conditions
A recentBlobscan Ethereum Mainnet snapshot shows blob gas pricing at only a few million wei per blob gas unit, equivalent to roughly 0.005 Gwei per blob gas in the snapshot reviewed for this article.
The same snapshot showed approximately 22 million blobs, around 4.5 million blocks, and about 2.67 TiB of total blob data size recorded on Ethereum Mainnet.
These figures change continuously, so they should be treated as a point-in-time snapshot rather than a permanent average.
They also illustrate an important feature of the blob market: prices can remain low when available blob capacity comfortably exceeds current demand.
A June 2026 Blobscan block example showed a blob gas price of approximately 0.011 Gwei, again indicating how low blob pricing can become during periods of relatively modest demand.
For live conditions, readers should use a current blob explorer rather than relying on a historical article snapshot.
Why Low Ethereum Blob Fees Do Not Guarantee Cheap L2 Transactions
It is tempting to conclude that low blob fees automatically mean extremely cheap L2 transactions.
The relationship is more complicated.
An L2 transaction can include several cost components:
L1 data publication
L2 execution
L2 operator fees
Proof generation
Proof verification
Sequencer-related costs
Network-specific overhead
For example, ZK-rollups may have additional proof-generation and verification costs that do not appear in the blob market itself.
Transaction complexity also differs between applications.
A simple token transfer may require less data than a more complex DeFi interaction.
Therefore, Ethereum Blob Fees are an important variable, but they are only one component of the final amount a user pays.
Ethereum Blob Fees and Rollup Compression
Compression is another major part of L2 fee economics.
Rollups do not necessarily publish every transaction in the same raw format used by users.
Instead, transaction data can be compressed and batched so that one Ethereum publication covers many L2 transactions.
This spreads the cost of posting data across a larger number of users.
Ethereum’sLayer 2 scaling documentation explains how rollups batch transactions and publish data to Ethereum to reduce per-transaction costs.
This is why changes in blob pricing can have different effects across rollups.
An L2 with efficient compression and large batches may respond differently from an L2 with higher data requirements.
Ethereum Blob Fees and Rollup Competition
A larger blob market can influence competition between Layer 2 networks.
When data availability is scarce and expensive, rollups face greater costs for posting batches.
As blob capacity increases, that constraint can become less severe.
This can give rollups more room to scale transaction throughput without paying the same data-publication cost.
Ethereum’s 2026 protocol roadmap continues to prioritize additional blob scaling. TheEthereum Foundation’s 2026 protocol priorities update states that further blob-parameter increases remain part of the broader scaling work.
This suggests the blob market is still an evolving component of Ethereum’s scaling architecture rather than a finished design.
Ethereum Blob Fees and Full Danksharding
Proto-Danksharding is not the final destination.
Ethereum’s longer-term danksharding roadmap aims to expand data availability substantially while using data-availability sampling.
TheEthereum Danksharding roadmap explains that later stages are designed to allow validators to verify blob availability through sampling rather than requiring every node to process the entire data set in the same way.
The objective is greater data capacity while preserving Ethereum’s security and decentralization properties.
Proto-Danksharding therefore provides the current infrastructure and fee market from which future scaling improvements can evolve.
How Traders and Developers Should Think About Ethereum Blob Fees
For developers building on L2s, blob economics can influence transaction costs, batching strategies, and application design.
For users, the main point is simpler:
L2 fees are not determined by Ethereum Mainnet gas alone.
Blob demand is another important variable.
When blob fees are low, rollups may face lower L1 data-publication costs. When demand rises and blob space becomes more competitive, those costs can increase.
A useful way to understand the market is to track:
Blob base fee
Blob utilization
Target vs maximum blob count
L2 transaction fees
Data-compression efficiency
Rollup activity
Ethereum execution fees
Readers following broader Ethereum developments can also explore Coin Network’sEthereum section and itsDeFi coverage for related network and market developments.
Common Misunderstandings About Ethereum Blob Fees
Blob Fees Are the Same as ETH Gas Fees
They are separate pricing mechanisms, even though both are measured through gas-like units.
Blobs Are Permanent Ethereum Storage
They are temporary data-availability objects rather than permanent archival storage.
Low Blob Fees Mean Every L2 Transaction Is Cheap
L2 fees include other components beyond blob publication.
More Blobs Always Mean Lower Fees
More capacity can reduce scarcity, but demand can increase at the same time.
Proto-Danksharding Is Full Danksharding-
Proto-Danksharding is an intermediate stage of Ethereum’s broader data-availability scaling roadmap.
Ethereum Blob Fees: Practical Checklist
When evaluating L2 cost trends, check:
Blob base fee: What is the current blob price?
Utilization: Is blob capacity heavily used?
Target: How many blobs does Ethereum currently target?
Maximum: What is the per-block maximum?
L2 data usage: How much data does the rollup publish?
Compression: How efficiently does the L2 batch transactions?
Execution fees: What does the L2 charge for computation?
Proof costs: Are proof-generation or verification expenses significant?
Network activity: Is L2 demand rising?
Capacity roadmap: Are additional blob increases planned?
Ethereum Blob Fees are a separate pricing mechanism for the temporary data space introduced by Proto-Danksharding.
EIP-4844 gave Layer 2 rollups a dedicated way to publish data to Ethereum, reducing reliance on more expensive calldata for rollup data.
Since its introduction, Ethereum has expanded blob capacity. By January 2026, the network had reached a 14-blob target and 21-blob maximum per block, providing substantially more L2 data capacity than the original Dencun configuration.
Current 2026 blob-market snapshots also show periods of very low blob pricing, although the fee can change as demand changes.
The most important takeaway is that blob fees should be viewed as one component of L2 economics, not as the entire transaction fee.
Rollup execution, data compression, operator costs, proof-related expenses, and Ethereum’s broader data-availability capacity all influence what users ultimately pay.
Proto-Danksharding therefore represents not simply a fee reduction, but a change in how Ethereum prices and supplies the data-availability resource needed for rollup scaling.
FAQs
1. What are Ethereum Blob Fees?
Ethereum Blob Fees are fees charged for using Ethereum’s temporary blob data space.
They operate through a separate blob-gas market introduced by EIP-4844.
2. What is Proto-Danksharding-Ethereum Blob Fees?
Proto-Danksharding is the first stage of Ethereum’s danksharding roadmap.
It introduced blobs through EIP-4844 to provide rollups with cheaper data availability.
3. Why were blobs introduced-Ethereum Blob Fees?
Blobs were introduced to give Layer 2 rollups a more efficient way to publish transaction data to Ethereum.
This can reduce an important component of L2 data-publication costs.
4. Are blob fees the same as Ethereum gas fees?
No.
Blob gas and normal execution gas use separate pricing mechanisms.
A transaction involving blobs can therefore have both execution-related and blob-related costs.
5. How are Ethereum Blob Fees calculated?
Blob fees depend on the amount of blob gas used and the current blob base fee.
Ethereum requires blob data to remain available for a limited serving period of roughly 18 days. Blobs are not designed to replace permanent archival storage.
8. Do lower blob fees automatically reduce L2 transaction fees?
They can reduce an L2’s data-publication costs, but the final user fee also depends on execution, operator charges, compression, proof costs, and other factors.
9. Do ZK-rollups use blobs?
Yes.
Ethereum’sZK-rollup documentation explains that ZK-rollups can publish data using blobs or calldata.
10. Do optimistic rollups use blobs?
Yes.
Optimistic rollups can publish compressed transaction data through blobs, reducing their dependence on calldata for data publication.