Smart Wallet Session Keys are temporary or restricted authorization methods that allow an application to perform certain blockchain actions without requiring the user’s main wallet key to sign every transaction.
The idea is to replace repeated full-wallet approvals with scoped permissions.
For example, a user could allow a game to spend up to 10 USDC per day, interact only with a particular contract, and automatically lose access after 24 hours. The application can then perform permitted actions within those limits without asking the user to approve every individual transaction.
TheERC-4337 documentation on session keys and delegation explains that session-key systems can grant permissions such as expiration times and target-contract restrictions, although implementations are still wallet- and module-specific rather than being a single native ERC-4337 feature.
This makes session keys an important part of the broader move toward programmable crypto wallets.
How Smart Wallet Session Keys Work
A traditional externally owned account generally relies on its main private key to authorize transactions.
That model is secure when the key is protected properly, but it can create a frustrating user experience. Every action may require another wallet confirmation.
A smart account can instead use programmable authorization logic.
A simplified session-key flow looks like this:
The user connects a smart wallet to an application.
The application requests a specific permission set.
The user approves the permitted actions.
A session key or delegated authorization is created.
The application performs actions within those limits.
The permission expires or is revoked.
The important security property is scope.
A session key should not automatically have the same authority as the user’s main wallet.
Depending on the implementation, restrictions may include:
Specific contracts
Specific functions
Specific tokens
Spending limits
Time windows
Number of transactions
Chain restrictions
Gas limits
TheERC-4337 session-key documentation describes static delegation and dynamic delegation models and notes that session-key enforcement is typically implemented through wallet plugins or authorization modules.
Why Smart Wallet Session Keys Matter
Smart wallets are designed to make blockchain accounts more programmable.
Ethereum’sAccount Abstraction roadmap, updated in June 2026, explains that smart accounts can support features such as customized security logic, recovery mechanisms, gas abstraction, and improved user experiences.
Session keys extend that concept by allowing an application to receive a limited authorization instead of unrestricted control.
This can be useful for:
Blockchain games
Automated trading interfaces
Recurring payments
Subscriptions
DeFi automation
AI agents
Portfolio management
Social applications
High-frequency dApp interactions
A user can potentially authorize a workflow once instead of repeatedly signing dozens of transactions.
Smart Wallet Session Keys vs Private Keys
The most important difference is the level of authority.
A traditional private key generally represents control over the account. Anyone who obtains that key can potentially sign transactions within the account’s capabilities.
A properly designed session key is intended to have narrower permissions.
For example:
Main wallet key: Broad account control
Session key: Trade only on one protocol, up to 50 USDC, until midnight
That difference can reduce the potential impact of a compromised session key.
However, the security depends on how the wallet and permission system enforce the restrictions.
A poorly implemented authorization mechanism can expose users to much greater risk than intended.
Smart Wallet Session Keys and ERC-4337
ERC-4337 provides a framework for smart accounts without requiring a fundamental Ethereum consensus-layer change.
TheERC-4337 documentation explains that smart accounts can support programmable validation, gas sponsorship, batching, and custom authorization.
ERC-4337 itself does not standardize one universal session-key format.
Instead, session keys can be implemented through smart-account modules, plugins, and delegation mechanisms.
This distinction matters because two wallets can both support ERC-4337 while implementing session permissions differently.
Smart Wallet Session Keys and ERC-7715
ERC-7715 focuses specifically on how decentralized applications request permissions from wallets.
TheERC-7715 specification defines a wallet_requestExecutionPermissions method that allows a dApp to request scoped permissions for executing transactions on a user’s behalf.
The goal is to make permission requests more structured than traditional token approvals.
MetaMask introduced its Advanced Permissions system in April 2026 using ERC-7715. The company describes the system as providing limited, time-bound permissions for use cases such as subscriptions, dollar-cost averaging, AI agents, vesting, and auto-compounding.MetaMask’s April 2026 announcement provides the implementation details.
MetaMask’s current documentation explains that users can configure limits such as spending amounts, frequency, and expiration dates through supported smart accounts.MetaMask’s Advanced Permissions guide provides examples.
Smart Wallet Session Keys and EIP-7702
EIP-7702 introduced another important piece of the smart-wallet ecosystem.
Ethereum’sEIP-7702 documentation allows an existing EOA to delegate execution to deployed smart-contract code through a new transaction type.
This means users can keep the same wallet address while gaining smart-account-style functionality.
Ethereum’s2026 development overview specifically identifies session keys, batching, gas sponsorship, and recovery flows as use cases enabled by EIP-7702.
EIP-7702 is therefore complementary to session-key systems.
The delegation itself is not necessarily the session permission. Instead, the delegated smart-account code can implement permission systems that support scoped authorizations.
This distinction is important when evaluating wallet security.
Smart Wallet Session Keys and Temporary Permissions
A session permission can be designed around several constraints.
Time Limit
The authorization expires after a defined period.
Example:
Valid for 24 hours
Spending Limit
The session can spend only up to a predetermined amount.
Example:
Maximum 100 USDC
Contract Restriction
The session may interact only with one or more approved contracts.
Example:
Only interact with a specific game contract
Function Restriction
The session can call selected contract functions but not others.
Example:
Swap only, no arbitrary token transfers
Chain Restriction
The permission may be limited to a specific blockchain.
These constraints reduce the scope of authority compared with giving an application unrestricted access.
Smart Wallet Session Keys and Security
Session keys are designed to reduce unnecessary exposure of a user’s primary signing authority, but they introduce a new security boundary.
The user must trust that:
The permission request accurately describes the intended scope
The wallet displays the permissions clearly
The smart-account module enforces the limits
The session key cannot bypass the restrictions
Expiration and revocation work as expected
This is why session permissions should be treated as security controls rather than simply convenience features.
Ethereum’s EIP-7702 guidance warns that delegated code is security-critical. If an account delegates to malicious or buggy code, that code can potentially make calls as the user.Ethereum’s EIP-7702 security guidance recommends trusted delegation contracts and careful wallet handling.
Smart Wallet Session Keys vs Traditional Token Approvals
Traditional token approvals generally grant another contract permission to spend a token.
Depending on the approval mechanism, this permission can remain active until the user changes or revokes it.
Session-based permissions can provide additional constraints.
Traditional approval: Often broad and potentially persistent
Scoped permission: Potentially limited by amount, action, contract, and time
Neither model is automatically safe. The security depends on the smart contract, wallet implementation, permission mechanism, and user’s approval.
Smart Wallet Session Keys in 2026
Account abstraction activity has reached a significant scale.
A currentBundleBear ERC-4337 dashboard reports approximately 1.299 billion UserOperations, 856 million bundle transactions, and 67.9 million accounts with at least one UserOperation in its cumulative dataset.
The same dashboard provides network-level and monthly activity data for chains using ERC-4337 infrastructure.
EIP-7702 adoption is also substantial. The currentBundleBear EIP-7702 dashboard reports approximately 56.6 million smart accounts, 242.8 million authorizations, and 102 million Set Code transactions in its cumulative metrics.
These figures are infrastructure-level measurements, not counts of unique human users, and the dashboards continuously update their datasets.
They nevertheless show that programmable-account infrastructure is operating at a scale where permission systems such as session keys have increasingly practical relevance.
Smart Wallet Session Keys and User Experience
One of the strongest use cases is reducing repetitive wallet confirmations.
Consider a blockchain game where a player makes dozens of small actions during a session.
Without scoped permissions, each interaction may require another wallet signature.
With a session authorization, the player could grant:
Access to the game contract
A small token spending allowance
A short expiration period
The game could then execute permitted actions automatically.
This can make blockchain applications feel closer to conventional applications while preserving user-controlled authorization boundaries.
Smart Wallet Session Keys for AI Agents
AI agents are another emerging use case.
An agent may need to perform transactions on a user’s behalf, but giving an AI system unrestricted control over a valuable wallet creates obvious risks.
A scoped session permission can potentially limit the agent’s authority.
For example:
Maximum spend: 25 USDC per day
Validity: 7 days
Allowed contract: one DeFi protocol
Allowed function: swap
Network: one specific chain
This does not eliminate agent risk, but it can reduce the consequences of an agent behaving incorrectly or being compromised.
MetaMask specifically identifies AI agents as one of the use cases for its 2026 Advanced Permissions implementation.MetaMask’s announcement describes session-based execution within approved permission scopes.
Smart Wallet Session Keys and Revocation
A temporary permission is useful only if users can understand and control it.
A robust permission system should provide mechanisms to:
View active permissions
See expiration times
Revoke permissions
Adjust spending limits
Identify approved applications
Identify approved contracts
Dynamic delegation models can also use explicit expiration timestamps or other conditions.
Users should therefore periodically review active permissions rather than assuming every temporary authorization disappears automatically.
Common Risks of Smart Wallet Session Keys
Overly Broad Permissions
A session key that can interact with arbitrary contracts is much less restrictive than one limited to a specific application.
Excessive Spending Limits
A permission allowing unrestricted spending can undermine the intended security benefit.
Long Expiration Periods
A session that lasts indefinitely provides less containment than one that expires automatically.
Malicious dApps
A legitimate-looking dApp can request permissions that are broader than necessary.
Vulnerable Modules
Session authorization often relies on wallet modules or smart-account code. Bugs in those components can create additional risk.
Poor Permission Visibility
Users cannot make informed decisions if a wallet does not clearly explain what an authorization permits.
How to Use Smart Wallet Session Keys Safely
Before approving a session permission, check:
Application
Is the dApp authentic?
Contract
Which contract addresses can the permission interact with?
Assets
Which tokens or NFTs are affected?
Limits
What is the maximum amount that can be spent?
Duration
When does the authorization expire?
Functions
Which operations are allowed?
Chain
Is the permission restricted to the intended network?
Revocation
Can the permission be cancelled later?
Coin Network’sCrypto Wallet Security guide provides broader guidance on wallet permissions, suspicious dApps, transaction review, and protecting long-term holdings.
Smart Wallet Session Keys: Practical Checklist
Before approving temporary wallet permissions, review:
Scope: What exactly can the session key do?
Contract: Which smart contracts are authorized?
Token: Which assets can be accessed?
Limit: How much can be spent?
Frequency: How often can actions occur?
Expiry: When does access end?
Chain: Which network is covered?
Key: Is the session key separate from the main wallet key?
Module: Which smart-account component enforces the rules?
Revocation: Can the permission be cancelled?
Visibility: Can the wallet show active permissions?
Recovery: What happens if the session key is compromised?
For broader blockchain concepts, Coin Network’sCryptopedia provides additional educational resources.
Conclusion
Smart Wallet Session Keys allow crypto applications to use restricted wallet permissions instead of requiring users to approve every action with their primary wallet key.
The concept fits naturally into the broader Account Abstraction ecosystem built around ERC-4337, EIP-7702, ERC-6900, ERC-7579, and ERC-7715.
The major benefit is flexibility. Users can potentially define permissions by time, spending amount, contract, function, asset, and network, making repeated blockchain interactions more convenient while reducing the scope of authority granted to an application.
The technology is still evolving, and session keys are not implemented identically across all wallets.
2026 adoption data shows that smart-account infrastructure is already operating at significant scale, with billions of ERC-4337 UserOperations and tens of millions of accounts appearing in current ecosystem datasets.
For users, the most important principle remains simple:
Temporary permission should mean limited permission.
Before approving a session, check exactly what the application can do, how much it can spend, when access expires, and whether the permission can be revoked.
FAQs
1. What are Smart Wallet Session Keys?
Smart Wallet Session Keys are temporary or restricted authorization mechanisms that allow applications to perform approved blockchain actions without requiring the user’s main wallet key to sign every individual transaction.
2. Are session keys the same as private keys?
No.
A main private key generally provides broad control over an account, while a session key is intended to operate within a limited permission scope.
3. Are session keys part of ERC-4337?
ERC-4337 enables programmable smart accounts that can support session-key functionality, but the ERC-4337 standard does not define one universal session-key format.
Session keys are generally implemented through wallet-specific modules, plugins, or authorization systems.
4. What is ERC-7715?
ERC-7715 defines a wallet interface that allows dApps to request scoped execution permissions.
It is designed to make permission-based interactions more structured and predictable.
5. What is EIP-7702?
EIP-7702 allows an existing Ethereum EOA to delegate execution to deployed smart-account code.
This enables features such as batching, gas sponsorship, recovery flows, and session-key-style functionality while allowing the user to retain the same address.
6. Can session keys have spending limits?
Yes.
A permission can be designed to restrict the amount of an asset that an application can use.
For example, a user could authorize spending up to 10 USDC per day.
7. Can Smart Wallet Session Keys expire?
Yes.
Time-based restrictions are one of the common session-key patterns. An authorization can specify a validity period so the permission stops working after a defined time.
8. Can session keys be revoked?
Depending on the wallet and implementation, users can revoke or replace permissions.
Users should verify that their particular wallet provides clear permission-management and revocation controls.
9. Are Smart Wallet Session Keys completely safe?
No.
They can reduce the scope of permissions, but vulnerabilities in wallet software, smart-account modules, dApps, contracts, or permission logic can still create risks.
10. Can session keys be used for AI agents?
Yes.
Limited permissions can allow an AI agent to perform predefined actions without giving it unrestricted access to a user’s main wallet.
MetaMask identifies AI agents as one use case for its 2026 Advanced Permissions system.
11. Are session keys useful for blockchain games?
They can be.
Games often require many small interactions, so a limited session authorization can reduce repeated wallet confirmations while keeping spending and contract access constrained.
12. Where can I learn more about Smart Wallet Session Keys?
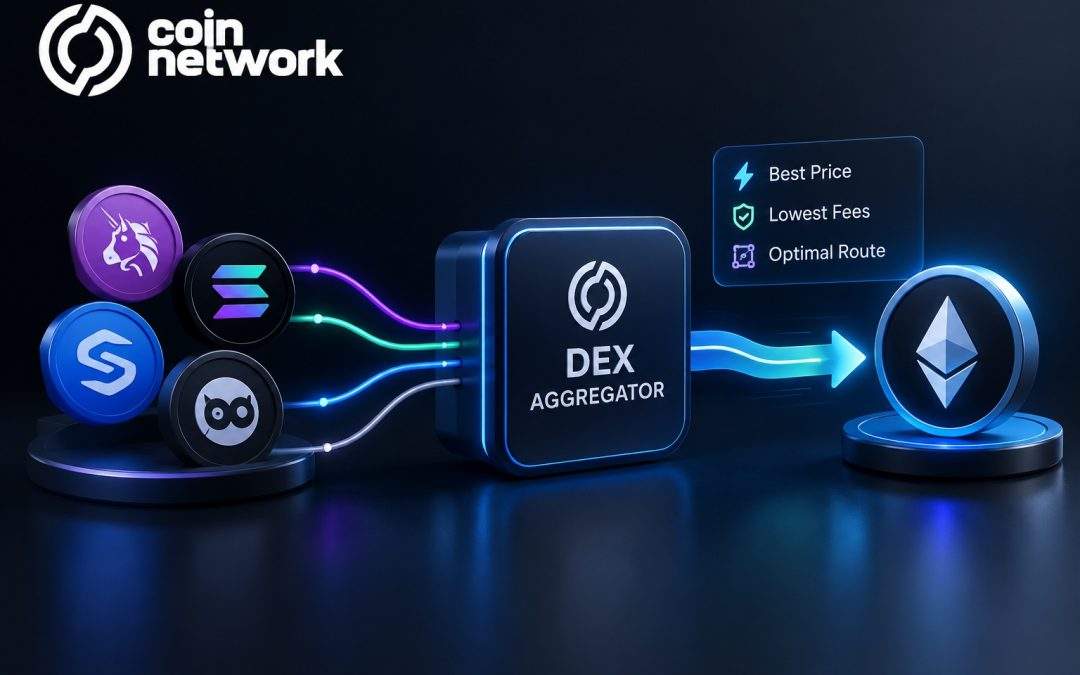
DEX Aggregators are crypto trading services that search across multiple decentralized exchanges and liquidity sources to determine a potentially better route for a token swap.
Instead of asking a trader to compare Uniswap, Curve, SushiSwap, Balancer, and other liquidity venues manually, an aggregator can evaluate available routes and present a single trade option.
Ethereum.org describes 1inch as an exchange aggregator that scans decentralized exchanges to find competitive prices, while its DeFi overview also lists aggregators such as CoW Swap that combine liquidity and routing strategies.Ethereum’s DeFi ecosystem overview provides broader context.
The main idea is simple:
More liquidity sources can give a routing system more options to compare.
However, the route with the highest quoted output is not always the route with the lowest total economic cost. Gas, price impact, fees, slippage, execution risk, and MEV can all matter.
How DEX Aggregators Work
A typical DEX aggregator performs several steps after a user enters a trade.
Suppose a trader wants to swap 10 ETH for USDC.
The aggregator can examine liquidity from multiple markets and estimate how much USDC each route could produce.
It might find:
Direct ETH → USDC on one DEX
ETH → USDT → USDC through two pools
ETH → WETH → USDC through another route
A split trade using several DEXs
A route combining AMM liquidity with professional market-maker liquidity
The routing engine then compares the expected outcome.
The user usually sees one quote even though the transaction may involve multiple liquidity sources.
The exact routing methods differ by provider, but the objective is generally to optimize execution rather than simply choose the exchange with the highest displayed token price.
DEX Aggregators and Liquidity Fragmentation
DEX liquidity is fragmented across many protocols and chains.
A token pair may have liquidity on multiple automated market makers, concentrated-liquidity pools, order-based systems, and professional market-maker networks.
This fragmentation creates both a challenge and an opportunity.
A trader using one DEX may see only the liquidity available on that platform.
An aggregator can compare several venues.
For example,1inch explains its aggregation model as a system that searches multiple DEXs and can split a trade among different liquidity sources.
The benefit can become more noticeable for larger trades because the trader is less dependent on a single pool.
DEX Aggregators and Smart Order Routing
Smart order routing is the main technology behind modern DEX aggregation.
The router can evaluate multiple paths instead of simply selecting the cheapest-looking pool.
Imagine these simplified options:
Route A: ETH → USDC = $30,000
Route B: ETH → USDT → USDC = $30,040
Route C: 60% through DEX A + 40% through DEX B = $30,090
A smart router may choose Route C because the combined result is better under the current liquidity conditions.
The calculation can include:
Expected output
Pool depth
Price impact
Trading fees
Gas costs
Route complexity
Available liquidity
Quote freshness
This is why the term “best route” should generally mean the best estimated execution result, not simply the highest quoted spot price.
DEX Aggregators and Split Trades
One important feature is the ability to split a transaction.
A large swap can move the price in one pool if that pool does not have enough liquidity.
Instead of sending the full transaction through one source, an aggregator can divide the order.
For example:
40% through DEX A
35% through DEX B
25% through DEX C
This can reduce the price impact associated with using one pool.
1inch’s routing documentation specifically describes transaction splitting as a way to spread larger trades across multiple liquidity sources.
However, splitting does not always improve the final result. Additional contract calls can increase gas consumption, and the optimal route depends on the size and structure of the trade.
DEX Aggregators and Multi-Hop Routes
Sometimes the best route is not a direct swap.
A token pair may have limited direct liquidity but deep liquidity through an intermediate asset.
For example:
TOKEN A → USDC → TOKEN B
or:
TOKEN A → WETH → TOKEN B
This is known as a multi-hop route.
Intermediate tokens can act as bridges between fragmented liquidity pools.
Uniswap’s technical walkthrough explains how swap paths can contain multiple exchanges, with routers moving through the specified sequence of pairs.
Aggregators can evaluate these paths alongside direct routes.
The trade-off is that more hops can mean more contract interactions, more gas, and potentially more execution complexity.
DEX Aggregators and Gas Costs
A route with the best token output is not necessarily the cheapest trade.
Suppose:
Route A returns $10,000 and costs $5 in gas.
Route B returns $10,015 but costs $25 in gas.
The second route has a higher gross output but may produce a worse net result after transaction costs.
Gas therefore needs to be included in route optimization.
This becomes especially important on Ethereum when network demand increases.
Ethereum’sDEX design guidance recommends displaying important trade information such as price impact, slippage, expected output, minimum received, gas cost, and other fees.
For traders, this means a good aggregator quote should be evaluated using net execution value, not just the headline output number.
DEX Aggregators, Slippage, and Price Impact
Slippage and price impact are related but different.
Price impact describes the effect that the trade itself has on the market price because of available liquidity.
Slippage is the difference between the expected execution and the amount ultimately received, including movements between quoting and execution.
An aggregator can reduce price impact by finding deeper liquidity or splitting a trade, but it cannot eliminate market movement.
A quote is also not guaranteed forever.
A fast-moving market can change before the transaction reaches the chain.
That is why users should review:
Expected output
Minimum received
Price impact
Slippage tolerance
Gas estimate
Quote expiry
DEX Aggregators and RFQ Liquidity
Modern aggregators do not always rely exclusively on public AMM pools.
Some also use RFQ, or Request for Quote, liquidity from professional market makers.
0x’s June 2026 documentation says its Swap API aggregates liquidity across 150+ DEXs and supports 20+ EVM-compatible chains. It also describes routing across AMMs and professional market makers.0x’s 2026 API overview provides the current details.
Its RFQ documentation states that for selected major trading pairs, RFQ liquidity produced a better price than AMMs around 52% of the time in its measured sample. The document also explains that 0x can combine RFQ and AMM liquidity in a single route.0x’s RFQ explanation provides the methodology and limitations behind that figure.
This is an important development because aggregation increasingly means comparing different types of liquidity, not merely different DEX pools.
DEX Aggregators and MEV
Maximum extractable value, or MEV, can affect swap execution.
A pending transaction can potentially be observed and reordered by market participants depending on the blockchain and transaction flow.
Some trading systems attempt to reduce exposure through private order flow, batch auctions, intent-based execution, or professional market-maker systems.
For example, Ethereum.org describes CoW Swap as a DEX aggregator that uses frequent batch auctions and peer-to-peer matching to seek liquidity while reducing certain forms of MEV exposure.Ethereum’s CoW Swap overview provides more context.
This means traders should not assume every aggregator uses the same execution model.
DEX Aggregators in 2026
DEX aggregation is now a substantial part of decentralized trading infrastructure.
A current DeFiLlama snapshot for Ethereum shows approximately $258.66 million in DEX-aggregator volume over 24 hours and $16.97 billion over 30 days. The same dashboard lists 1inch at roughly $2.13 billion in 30-day aggregator volume, 0x at about $2.58 billion, and CoW Swap at around $3.15 billion.DeFiLlama’s Ethereum DEX Aggregator dashboard provides the continuously updated figures.
For comparison, DeFiLlama’s Ethereum DEX dashboard currently shows approximately $557.46 million in 24-hour DEX volume and $39.51 billion over 30 days.The Ethereum DEX volume dashboard provides the corresponding ecosystem-wide snapshot.
These figures should be treated as live market data rather than fixed 2026 annual totals. Aggregator volume can also involve overlapping liquidity sources and different reporting methodologies, so simple comparisons between individual dashboards should be made carefully.
DEX Aggregators: What Makes a Route “Best”?
The best route depends on what the trader is optimizing.
A route can be evaluated based on:
Highest Expected Output
Useful when price is the primary concern.
Lowest Total Cost
Combines output, gas, and applicable fees.
Lowest Price Impact
Important for larger or less liquid trades.
Lowest Execution Risk
A simpler route may have fewer moving parts.
MEV Protection
Relevant when transaction ordering could materially affect execution.
Fast Execution
Some systems prioritize execution reliability over a small theoretical improvement in output.
The best aggregator therefore is not necessarily the one that always displays the highest quote. It is the one whose execution model best matches the user’s priorities and the current market.
Limitations of DEX Aggregators
Aggregation does not eliminate trading risks.
An aggregator can still route through:
Low-liquidity pools
Vulnerable protocols
Token contracts with transfer restrictions
Tokens with unusual taxes
Reverting liquidity sources
Complex multi-hop paths
A routing engine also depends on accurate quotes and available liquidity.
Users should inspect the final transaction before signing and verify that the received amount, token address, slippage limit, and contract interaction match their intentions.
For broader crypto-security education, Coin Network’sCryptopedia can be useful alongside itsDeFi coverage.
How to Use DEX Aggregators Safely
Before confirming a swap:
Check the Token
Verify the contract address rather than relying only on the ticker.
Compare the Quote
Look at expected output, price impact, and total fees.
Review the Route
Understand whether the trade is direct, split, or multi-hop.
Check Slippage
A very high slippage tolerance can expose a trade to worse execution.
Review Gas
A complex route may require more gas.
Check Approvals
Confirm which token and spender the approval transaction targets.
Review the Final Transaction
Make sure the destination contracts and output assets match the intended trade.
Coin Network’scrypto wallet security guide provides additional guidance on approvals, suspicious dApps, and transaction review.
Common Mistakes When Using DEX Aggregators
Assuming the Aggregator Guarantees the Best Price
Quotes change rapidly and depend on the available liquidity and gas conditions.
Ignoring Gas Costs
A slightly better gross output can become worse after execution costs.
Using Excessive Slippage
A generous slippage setting may make a trade more tolerant but can also increase execution risk.
Ignoring Price Impact
A route can still produce significant market impact when liquidity is thin.
Assuming Every Route Is Equally Safe
Different routes can interact with different contracts and liquidity sources.
Comparing Only the Headline Token Output
Always consider fees, gas, price impact, and minimum received.
DEX Aggregators: Practical Checklist
Before confirming a crypto swap, check:
Quote: What is the expected output?
Route: Which DEXs or liquidity sources are being used?
Split: Is the trade divided among multiple pools?
Price impact: How much does the order move the market?
Slippage: What is the maximum acceptable execution difference?
Gas: How much will the transaction cost?
Fees: Are there aggregator or protocol fees?
Token: Is the contract address correct?
Approval: Which spender receives token permission?
MEV: Is the execution model exposed to ordering risk?
Minimum received: What is the minimum output after tolerance?
Transaction: Does the final wallet request match the quote?
Conclusion
DEX Aggregators make decentralized trading more efficient by comparing fragmented liquidity and automatically selecting or constructing routes for token swaps.
Instead of relying on a single DEX, traders can access direct routes, multi-hop paths, split trades, and in some cases professional RFQ liquidity.
The current 2026 market data shows that aggregation is already a substantial part of Ethereum’s trading infrastructure, with DeFiLlama currently recording about $258.66 million in 24-hour Ethereum DEX-aggregator volume and approximately $16.97 billion over 30 days.
However, aggregation is not the same as a guarantee of perfect execution.
Gas, price impact, slippage, MEV, liquidity quality, token behavior, and smart-contract risk can all affect the final result.
The most useful approach is to treat a DEX aggregator as a routing and execution tool, then review the proposed transaction before signing.
The key question is:
Does the selected route provide the best overall execution after liquidity, price impact, gas, fees, and execution risk are considered?
FAQs
1. What are DEX Aggregators?
DEX Aggregators are platforms or protocols that compare liquidity across multiple decentralized exchanges and attempt to find an efficient route for a token swap.
2. How do DEX Aggregators find the best route?
They compare available liquidity, prices, fees, gas requirements, and potential paths across different sources.
Some systems can split a trade or use multiple hops when that produces a better estimated result.
3. Are DEX Aggregators better than using one DEX?
They can provide more routing options because they can compare multiple liquidity sources.
However, the best choice depends on the trade, chain, liquidity conditions, gas costs, and execution model.
4. Can DEX Aggregators split a trade?
Yes.
A routing system can divide a single order among multiple liquidity sources when doing so is expected to improve execution.
5. What is smart order routing?
Smart order routing is the process of evaluating multiple possible execution paths and selecting a route based on factors such as output, liquidity, price impact, gas, and fees.
6. What is a multi-hop swap?
A multi-hop swap passes through one or more intermediate assets.
For example, a trade might use Token A → USDC → Token B instead of exchanging Token A directly for Token B.
7. Do DEX Aggregators reduce slippage?
They can reduce price impact by finding deeper liquidity or splitting trades, but they cannot eliminate market movement or guarantee a specific execution price.
8. Do DEX Aggregators charge extra fees?
Some aggregators may charge a routing or service fee, while others monetize through other mechanisms.
Traders should review the quote’s fee information before signing.
9. What is RFQ liquidity in a DEX Aggregator?
RFQ, or Request for Quote, allows professional market makers to provide trade-specific quotes.
Some aggregators compare those quotes with public AMM liquidity and use whichever route offers the stronger execution result.
10. Can DEX Aggregators protect against MEV?
Some execution systems are designed to reduce particular MEV risks, but protection varies by aggregator and transaction method.
OKXICE, the joint venture between crypto exchange OKX and Intercontinental Exchange (ICE), the parent company of the New York Stock Exchange, has filed with the U.S. Securities and Exchange Commission to launch a venue for tokenized stock trading that would operate 24 hours a day, seven days a week. The notice, dated Sunday, October 4, relies on the SEC's new Innovation Exemption, which the agency issued on September 17 to let qualifying venues trade tokenized U.S. stocks using automated market makers and liquidity pools without registering as exchanges.
The filing matters because it puts the SEC's five-year exemption into practice for the first time at this scale, pairing a major U.S. exchange operator with one of the largest crypto platforms. The plan covers 63 stock tokens and remains subject to regulatory steps, including a 30-day window during which listed companies can object to the tokenization of their shares.
What OKXICE Filed
OKXICE LLC notified the SEC that it intends to operate as a Tokenized Securities Venue, or TSV, a new category of platform the agency created through its September 17 order. The venture plans to run permissioned Uniswap v4 liquidity pools on X Layer, OKX's layer-2 network, offering around-the-clock trading in more than 60 U.S.-listed companies.
The initial list of 63 stock tokens includes Nvidia, Tesla, Apple, Microsoft, Amazon, JPMorgan and Goldman Sachs, along with crypto-linked companies such as Coinbase, Strategy, Circle and Robinhood, according to reports by Cointelegraph and Yahoo Finance. Each tokenized stock would be paired with USDC, Global Dollar (USDG) or USDt, Cointelegraph reported.
The tokens listed so far come from a third-party tokenizer, which the notice does not name, that holds the underlying shares one-for-one through an SEC-registered broker-dealer, Yahoo Finance reported. The notice also states that OKXICE is not registered with the SEC in any capacity for this activity, according to Finance Magnates.
The SEC Innovation Exemption Behind Tokenized Stock Trading
The SEC order grants temporary, conditional exemptive relief to Tokenized Securities Venues from the definition of "exchange" in the Securities Exchange Act of 1934, allowing them to trade tokenized National Market System stock through permissioned automated market makers and liquidity pools. The relief was issued under Section 36(a)(1) of the Exchange Act and also exempts certain liquidity providers, called Covered Firms, from the definition of "dealer."
SEC Chairman Paul Atkins framed the order as a deliberate policy choice. Today, the Securities and Exchange Commission is taking a significant step forward, within its statutory authority, to bring America's capital markets into the digital age by facilitating onchain trading of certain tokenized stocks through the 'Innovation Exemption,' he said. Jamie Selway, Director of the SEC Division of Trading and Markets, called the approval "an important milestone for the Commission's work to open our capital markets for tokenized securities."
The exemption carries conditions. Tokenized NMS stocks traded on a TSV face limits on the number of symbols and volume traded; each venue may list no more than 75 large U.S. stocks, with volume capped at 0.25 percent of each stock's average daily volume, according to Trending Topics. A TSV must verify that tokenized stock gives holders the same rights and privileges as the equivalent traditional shares, including dividends and voting rights, and must stop trading a token whenever the underlying stock is halted on its primary listing exchange.
Issuers retain a say in the process. Before a TSV lists a stock tokenized by an unaffiliated third party, it must give the underlying issuer written notice and an opportunity to object, and issuers that do not want their shares trading on such venues can opt out. Smart contracts used by a TSV must be auditable, public and deployed on a public, permissionless distributed ledger, and venues must provide public notice about their operations and trading activities.
The SEC described the relief as an interim step. The Innovation Exemption would allow TSVs to trade tokenized NMS stock in a permissioned environment today while the Commission considers the need for additional action to facilitate onchain trading, the agency said, adding that insights gained during the temporary window will inform durable, comprehensive rules. The order will be published on SEC.gov and in the Federal Register.
Cuomo and Xu on the 24/7 Plan
Andrew Cuomo, the former New York governor who co-chairs OKXICE, announced the filing on X on Sunday night. "This is a landmark step toward a truly global, 24/7 Wall Street — and toward keeping the future of digital finance anchored here in the United States," Cuomo said in a statement shared with The Block, adding that "Tokenized securities are part of what comes next."
Cuomo told CoinDesk the venture combines strengths from both parents, saying OKX and ICE bring together deep expertise from both sides of the equation. The opportunity now is to build on this first step and show how 24/7, onchain markets can make trading and settlement more efficient, accessible and global, he said, adding: "And we're just getting started."
Star Xu, founder and chief executive of OKX, emphasized the shareholder-rights condition at the center of the SEC framework. The future of markets is real ownership, onchain. Full shareholder rights are what make that possible, Xu said, according to The Block and Trending Topics. He also said tokenization could make public markets "more open, seamless and always available."
The venture is co-chaired by Cuomo and Trabue Bland, Senior Vice President of Futures Exchanges at ICE, The Crypto Times reported. Cuomo also sits on the OKX board of directors, a role The Crypto Times reported in July after he spent several years as an adviser to the exchange.
The OKX-ICE Partnership Behind the Venue
OKX and ICE announced OKXICE as a 50-50 joint venture on June 22, 2026, to build infrastructure for tokenized and digitally native financial products. The venture followed ICE's strategic investment in OKX in March 2026, a deal that valued the crypto exchange at about $25 billion.
Under the broader arrangement, OKX customers could gain access to ICE futures and tokenized NYSE shares, subject to regulatory approval, according to ICE's announcement. The two companies have since expanded their ties, including the launch of OKX perpetual futures based on ICE oil benchmarks in May, The Crypto Times reported.
OKX already operates tokenized stocks outside the U.S. under the xStocks brand, covering over 70 U.S. equities and ETFs settled on Solana and X Layer and priced in USDT, according to Coingape. OKXICE now wants to bring that trading onshore to a regulated U.S. venue, where tokenized versions of stocks carry the same dividend and voting rights as regular shares, CoinDesk reported.
OKB, the native token of the OKX ecosystem, traded at $124.62 at the time of writing, up 3.4% over 24 hours and 5.3% over seven days, according to CoinGecko data cited by The Crypto Times.
Industry Pushback and What Comes Next
Not all market groups support the SEC's approach. SIFMA, the trade group for U.S. securities firms, warned that the exemption could allow multiple tokenized versions of the same stock to trade in parallel on lightly regulated markets, which could confuse and harm investors, its chief executive Kenneth Bentsen said in a statement, according to Trending Topics.
Better Markets, an advocacy group, was blunter. "The SEC has essentially created two regulatory regimes for stock trading," said Benjamin Schiffrin, its director of securities policy.
The filing lands amid a broader industry push toward extended trading hours. Nasdaq is set to move to 23-hour trading five days a week in December, while the London Stock Exchange is preparing its own 24/5 venue for 2027, DailyCoin reported. The SEC also approved a Nasdaq pilot in March in which tokenized shares trade in the same order book and under the same ticker as conventional ones, according to Finance Magnates.
OKXICE enters a race that includes Ondo, Robinhood and NYSE's separate tokenized-stock access talks with Blockchain.com, Coingape reported. Robinhood is reportedly approaching SEC volume caps under the same exemption framework.
Before trading can begin, OKXICE must complete the 30-day issuer opt-out period and meet every condition of the exemption, including symbol limits, volume caps and full shareholder rights for token holders. The number of companies that remain on the initial list of 63 will indicate how willing NYSE-listed issuers are to see their shares traded on blockchain-based venues, and the SEC has said it will use data from the five-year window to shape longer-term rules for tokenized securities.
Conclusion
OKXICE's October 4 filing is the first large-scale attempt to use the SEC's Innovation Exemption, proposing 24/7 trading of 63 tokenized U.S. stocks on X Layer through permissioned Uniswap v4 pools. The venue still faces concrete steps before launch: a 30-day window for issuers to object to tokenization of their shares, plus compliance with the exemption's conditions on symbol limits, volume caps, shareholder rights and halt linkages. The SEC has said it will use observations from the five-year exemption period to develop permanent rules for onchain trading of tokenized securities.
Frequently Asked Questions
What is OKXICE and who owns it?
OKXICE is a 50-50 joint venture between crypto exchange OKX and Intercontinental Exchange, the parent company of the New York Stock Exchange. The two companies announced the venture on June 22, 2026, to build infrastructure for tokenized and digitally native financial products, following ICE's March 2026 investment in OKX at a valuation of about $25 billion.
Which stocks will OKXICE's tokenized stock trading venue offer?
The notice lists 63 stock tokens, including Nvidia, Tesla, Apple, Microsoft, Amazon, JPMorgan and Goldman Sachs, plus crypto-linked companies such as Coinbase, Strategy, Circle and Robinhood. The tokens come from an unnamed third-party tokenizer that holds the underlying shares one-for-one through an SEC-registered broker-dealer.
What is the SEC Innovation Exemption issued on September 17, 2026?
The Innovation Exemption is a five-year SEC order granting temporary, conditional relief that lets Tokenized Securities Venues trade tokenized U.S. stocks through permissioned automated market makers and liquidity pools without registering as exchanges. It also exempts certain liquidity providers from the definition of "dealer" under the Securities Exchange Act of 1934.
When can OKXICE begin 24/7 trading of tokenized stocks?
No launch date has been set. OKXICE must first complete a 30-day period during which issuers can object to the tokenization of their shares, and it must meet all exemption conditions, including symbol limits, volume caps and full shareholder rights for token holders, before trading can begin.
What protections does the SEC require for tokenized stock holders?
Tokenized stocks must give holders the same rights and privileges as traditional shares, including dividends and voting rights. Trading in a token must stop whenever the underlying stock is halted on its primary exchange, venues may list no more than 75 large U.S. stocks, and volume is capped at 0.25 percent of each stock's average daily volume.
Metaplanet bitcoin holdings climbed to 44,000 BTC, valued at roughly $3.8 billion, after the Tokyo-listed treasury firm added a net 1,000 BTC during the third quarter, the company disclosed Monday. The increase followed an unusual sequence in which the company sold 10,000 BTC and then bought 11,000 BTC before the period ended Sept. 30.
The transactions matter because they were built to show creditors, rating agencies and fixed-income investors that the company's bitcoin reserves can be turned into cash if required. Metaplanet framed the exercise as a way to strengthen how its creditworthiness is perceived and to open wider access to bonds, preferred shares and other financing channels.
Metaplanet Bitcoin Holdings After the Q3 Round Trip
According to CoinDesk, the Japanese firm parted with 10,000 BTC for roughly $789.2 million at an average price of $78,925 per coin, then spent $948.7 million acquiring 11,000 BTC at an average of $86,246 each. Bitcoin.com News put the sale proceeds at $789.5 million, or 124.7 billion yen, an amount the company said surpassed its outstanding bonds, borrowings and other interest-bearing liabilities once cash and dollar stablecoins were accounted for.
For a period, the company parked the sale proceeds in cash, showing it had enough on hand to cover its interest-bearing obligations even though none of that debt was actually paid off. In total, the firm converted enough of its stash into cash to surpass the outstanding principal across all of its interest-bearing liabilities before buying the position back.
Executing a real sale, rather than citing theoretical market depth, was meant to prove the company could and would convert bitcoin into cash if obligations or other capital-management needs demanded it. Gerovich said the buyback exceeded the amount sold, producing a net gain of 1,000 BTC for the quarter.
At 44,000 BTC as of Sept. 30, Metaplanet bitcoin holdings now rank the company as the world's second-largest listed bitcoin treasury firm. Its reserves have expanded from 30,823 BTC in October 2025 to the current level.
Revised Capital Allocation Keeps 85% to 90% in Bitcoin
Alongside the transactions, Metaplanet overhauled its capital-allocation framework. The updated policy directs that roughly 85% to 90% of total assets remain in bitcoin, with 10% to 15% freed up for acquisitions and investments that produce income.
That smaller portion may fund deals that bolster the company's bitcoin financial platform, investments yielding recurring income, and seed capital for a planned asset management arm. Qualifying investments may also include overseas bitcoin-linked securities, among them preferred securities from other bitcoin treasury firms.
Even with the new flexibility, the company confirmed bitcoin stays at the core of its treasury strategy, pledging to grow both its overall stack and its bitcoin-per-share figure over the medium to long term. According to bloomingbit, the firm also wants to broaden its funding toolkit through corporate bonds and preferred-share issuance, channeling that capacity into further growth of Metaplanet bitcoin holdings.
New common stock will be issued sparingly, generally reserved for moments when the company's mNAV sits above 1.0x and management judges a sale would benefit current shareholders. The company defines mNAV as its enterprise value relative to the market value of its bitcoin stack; it weighed such an issuance in June when the ratio fell to 0.92x.
Net Interest Income Strategy and Project Nova
Metaplanet is pairing the revised asset allocation with a new Net Interest Income Strategy built to produce recurring cash flow. The approach draws on financing from preferred stock, bonds and bitcoin-backed credit facilities, deploying the money into assets that generate steady income and capturing the spread over funding costs.
The company said such investments will proceed only when the anticipated yield, adjusted for credit risk, clears its total cost of capital by a sufficient margin. Gerovich described the strategy as a way to build recurring income streams while reducing the company's effective cost of capital.
Project Nova serves as the umbrella for building financial businesses around the bitcoin treasury. A central piece is Metaplanet Securities, a regulated brokerage formed after the firm completed its 2.1 billion yen acquisition of Siiibo Securities in July, giving it an in-house platform to issue and distribute corporate bonds, preferred stock and other financial products.
The company also agreed in August to exchange 2,100 BTC plus $2.5 million in cash for common stock, Strategic Alliance Preferred Stock and other securities in U.S.-based Super League Enterprise. Completion would give Metaplanet the right to appoint a majority of that company's board, and the deal is expected to close in the fourth quarter of 2026.
Cash flow from these ventures is meant to reinforce the company's financing capacity and, over time, supply capital for further bitcoin purchases. Metaplanet also intends to use income from its strategic investments as evidence that it can generate returns from assets outside its core BTC reserves.
Income Generation Revenue Falls; Shares Edge Higher
Revenue from the company's options-driven Bitcoin Income Generation unit came in at about $5.4 million for the third quarter, a drop of 51% from the prior quarter and 65% from a year earlier, according to CoinDesk. The decline arrived as the firm reworks how it earns income around its treasury.
The company also gave a preliminary estimate that its subsidiaries may be able to book a deferred tax asset of roughly $97 million tied to the transactions, though auditors have yet to confirm whether recognition is permitted, Bitcoin.com News reported.
September also brought a 41.1% reduction in potential dilution from the company's Series 10 stock acquisition rights, shrinking the potential share pool from 319.46 million shares to 188.19 million. Separately, the firm has begun preliminary consultations with the Tokyo Stock Exchange about listing its preferred stock.
Metaplanet shares ended Monday's session up 2% at 297 yen, equivalent to $1.88.
Gerovich: Strategy Was Never Just Accumulation
In a post on X, Gerovich explained that the third-quarter sale and repurchase were carried out to show the market that the company's reserves are liquid. He has consistently framed the moves as part of a broader ambition that goes beyond stacking coins.
"From the beginning, our strategy was never simply to accumulate bitcoin," Gerovich said. He added that the company's goal is to become a leading bitcoin financial institution by growing its reserves, operating businesses, capital access and credit infrastructure.
In separate comments reported by CoinDesk, Gerovich said: "Our objective has been to build the leading Bitcoin financial company in Asia."
The company launched its BitBonds program in August through four private bond placements totaling around 200 million yen, distributed to eligible investors under Japan's private placement framework via Metaplanet Securities. Borrowing backed by bitcoin is intended as temporary funding that will progressively be converted into permanent capital, with liabilities matched against asset cash flows under an asset-liability management approach.
Conclusion
Metaplanet closed the third quarter holding 44,000 BTC valued at about $3.8 billion, having sold 10,000 BTC and repurchased 11,000 BTC in a round trip it said proved the treasury can be turned into cash without retiring any of its debt. The disclosure arrived alongside a reworked capital-allocation policy that keeps 85% to 90% of assets in bitcoin and a Net Interest Income Strategy aimed at recurring cash flow.
The next concrete steps include the planned fourth-quarter 2026 closing of the Super League Enterprise investment, in which Metaplanet committed 2,100 BTC and $2.5 million, and continued consultations with the Tokyo Stock Exchange over listing its preferred stock. The company said it intends to use its secured financing capacity to further increase its bitcoin holdings.
Frequently Asked Questions
How many bitcoin does Metaplanet hold after the third quarter of 2026?
Metaplanet held 44,000 BTC as of Sept. 30, valued at roughly $3.8 billion, after adding a net 1,000 BTC during the third quarter. The company disclosed the figure on Monday, and the balance makes it the second-largest listed bitcoin treasury company in the world.
Why did Metaplanet sell 10,000 BTC and then buy 11,000 BTC?
The company said the round trip was staged to prove its bitcoin reserves are liquid and can be turned into cash if needed, with the goal of strengthening its credit profile among rating agencies and fixed-income investors. Proceeds were parked in cash, showing it could cover interest-bearing debt without repaying it, before the position was rebuilt larger.
What is Metaplanet's revised capital allocation policy for bitcoin?
The updated framework directs that roughly 85% to 90% of total assets stay in bitcoin, while 10% to 15% can go toward acquisitions and income-generating investments. Bitcoin remains the primary treasury reserve asset, and the company has pledged to expand both its aggregate stack and the amount of bitcoin backing each share over the medium to long term.
What is Metaplanet's Net Interest Income Strategy?
The strategy raises money through preferred stock, bonds and bitcoin-backed credit facilities, then invests in assets that produce recurring cash flow so the company earns a spread over its funding costs. Gerovich said the approach is designed to create recurring income streams and lower the firm's effective cost of capital.
How did Metaplanet's Bitcoin Income Generation revenue perform in Q3 2026?
The options-based unit brought in roughly $5.4 million during the third quarter, a decline of 51% from the second quarter and 65% from a year earlier, according to CoinDesk. The drop came as the company reshapes how it earns income around its treasury operations.
Stablecoin Depegging occurs when a token designed to maintain a value close to $1 moves materially above or below that reference price.
A stablecoin may trade at $0.99, $0.95, or substantially lower during a stress event. It can also trade above $1 when demand for the token exceeds the available market supply or when local liquidity conditions create a premium.
A temporary difference of a few basis points does not necessarily represent a structural failure. Stablecoins trade across multiple exchanges, blockchains, liquidity pools, and markets, so small deviations can occur during normal trading.
A more serious depeg can emerge when market participants lose confidence in the issuer, reserve assets, redemption mechanism, collateral, or smart-contract system.
The core question is:
Why are market participants no longer willing or able to exchange the stablecoin for approximately $1?
How a Dollar-Peg Is Supposed to Work
The mechanics depend on the type of stablecoin.
A fiat-backed stablecoin generally relies on reserves such as cash, Treasury bills, bank deposits, or other highly liquid assets. The issuer creates tokens when users provide the required assets and redeems tokens when users return them.
For example, Circle states that USDC is designed to be redeemable 1:1 for U.S. dollars and that its reserves consist of cash and cash-equivalent assets. Circle’scurrent transparency page publishes reserve information and issuance and redemption data.
Other stablecoins use different models.
Fiat-Backed Stablecoins
These rely primarily on off-chain reserves and an issuer or redemption system.
Crypto-Backed Stablecoins
These use cryptocurrency collateral, often with excess collateral to absorb price movements.
Algorithmic or Hybrid Stablecoins
These attempt to maintain their target value through market incentives, collateral structures, trading mechanisms, or combinations of these systems.
Because the underlying mechanisms differ, the causes and severity of a depeg can also differ.
Stablecoin Depegging Caused by Reserve Concerns
One of the most important potential causes of Stablecoin Depegging is uncertainty about reserves.
If holders believe that the issuer does not have enough high-quality assets to meet redemptions, they may rush to sell the stablecoin before other holders do.
The market does not necessarily need proof of an actual reserve shortfall. A sudden loss of confidence can itself create significant liquidity pressure.
This is why reserve transparency, redemption arrangements, custody, and asset quality are important components of stablecoin risk analysis.
Stablecoin Depegging and Redemption Pressure
A stablecoin’s peg depends partly on arbitrage.
If a token trades at $0.98 but can reliably be redeemed for $1, an eligible market participant may have an incentive to buy the token at $0.98 and redeem it for $1.
That process can help bring the market price closer to its target.
However, arbitrage only works efficiently when redemption is accessible and sufficiently fast.
Problems can arise when:
Redemption is restricted
Redemptions have delays
Certain users cannot redeem directly
Banking rails are disrupted
Market makers lack liquidity
Redemption costs become significant
A stablecoin can therefore remain below $1 longer when the normal arbitrage mechanism is impaired.
Stablecoin Depegging and Liquidity Shocks
Liquidity is another major factor.
A stablecoin may have substantial total market capitalization but still experience temporary price dislocations in specific trading pools or regions.
A thin order book or shallow decentralized-exchange pool can amplify a relatively modest sell order.
This became visible in June 2026 when USDT traded at a premium of more than 8.5% over its dollar reference price on some Indian crypto platforms after enforcement actions disrupted parts of the local supply pipeline.CoinDesk’s June 2026 report on the Indian USDT premium described the event as a local liquidity and supply disruption rather than a failure of USDT’s global dollar peg.
This example is important because not every deviation from $1 has the same cause.
A regional premium can result from fragmented liquidity even when the global market continues trading close to $1.
Stablecoin Depegging During Crypto Market Stress
Large market sell-offs can increase stablecoin volatility indirectly.
During periods of extreme crypto-market stress:
Traders may rush into stablecoins
Crypto-backed collateral can fall sharply
DeFi positions can be liquidated
Liquidity providers can withdraw capital
Market makers can reduce risk
Borrowing costs can change
Stablecoin redemptions can accelerate
For crypto-backed systems, falling collateral values can be particularly important because the stablecoin’s backing may itself be volatile.
A collateralized stablecoin may therefore require liquidation mechanisms or additional collateral to maintain its target.
Stablecoin Depegging and Collateral Liquidations
Crypto-backed stablecoins often depend on collateral being worth more than the stablecoins issued against it.
Suppose a protocol issues $100 million of stablecoins against $150 million of volatile crypto collateral.
If collateral falls sharply, the safety buffer becomes smaller.
The protocol may then liquidate collateral to maintain the required backing ratio.
If liquidations occur during a market-wide sell-off, liquidity can become more difficult to obtain precisely when it is most needed.
This can increase the risk of further price dislocations.
The specific risk depends on the collateral type, liquidation rules, oracle design, and available liquidity.
Stablecoin Depegging and Smart Contract Exploits
A stablecoin can also lose its target price because of a technical exploit.
In March 2026, the Resolv USR stablecoin experienced a severe depeg after an attacker exploited weaknesses in its minting system. CoinDesk reported that the attacker created about 80 million unbacked USR tokens and extracted roughly $25 million in ETH. USR fell to around $0.02 at one point and was trading well below $1 afterward.CoinDesk’s March 2026 report on the Resolv incident described missing mint limits, inadequate validation, and privileged-account weaknesses as important parts of the incident.
The event illustrates an important point:
Stablecoin Depegging can result from smart-contract failures even when the original problem is not a traditional reserve shortage.
The actual risk depends on the architecture of the stablecoin.
Stablecoin Depegging and Oracle Failures
Some DeFi stablecoins depend on price oracles to determine collateral values, liquidation thresholds, or minting conditions.
An inaccurate, manipulated, delayed, or unavailable oracle can cause a protocol to make incorrect decisions.
Potential consequences can include:
Excessive minting
Improper liquidations
Under-collateralized positions
Incorrect collateral valuations
Market dislocations
Oracle dependency is therefore especially important for decentralized stablecoins and other collateral-based protocols.
Users should examine which oracle providers a stablecoin uses and what happens if those feeds become unavailable or manipulated.
Stablecoin Depegging and Exchange Liquidity
Stablecoins trade on centralized exchanges, decentralized exchanges, peer-to-peer markets, and payment platforms.
Their prices can therefore differ temporarily between venues.
A large exchange withdrawal, liquidity-provider exit, market-maker reduction, or regional disruption can cause one venue to show a more significant deviation than another.
The broader stablecoin market has become large enough that liquidity fragmentation matters.
CoinDesk Research reported that the total stablecoin market capitalization reached approximately $311 billion at the end of August 2026, up 1.19% during the month. The same report noted that USDT remained the largest stablecoin and that euro stablecoins also reached a record market capitalization.CoinDesk’s August 2026 stablecoin report provides the market data and methodology.
A separate September 25, 2026 market snapshot from Stablecoin Beat placed total tracked stablecoin capitalization at approximately $304.8 billion, with USDT around $183.8 billion and USDC around $75.3 billion.Stablecoin Beat’s market-cap dashboard provides the underlying time-series data.
The difference between the two figures reflects different dates, datasets, and measurement methods rather than necessarily indicating a market collapse.
Stablecoin Depegging and USDC Scale in 2026
USDC provides a useful example of how large the stablecoin sector has become.
Circle reported that USDC circulation reached $73.3 billion at the end of Q2 2026, representing 19% year-over-year growth. Circle also reported $14.8 trillion in USDC on-chain transaction volume during Q2 2026, a 151% year-over-year increase.Circle’s Q2 2026 results provide the company-reported figures.
By September 24, Circle’s transparency page showed approximately $75.2 billion of USDC in circulation.Circle’s latest USDC transparency information provides the current reserve and circulation disclosures.
These figures demonstrate why stablecoin confidence matters beyond individual trading pairs: stablecoins function as major settlement and liquidity instruments across crypto markets.
How Stablecoin Depegging Can Become a Feedback Loop
A serious depeg can become self-reinforcing.
Consider a simplified sequence:
Investors become concerned about reserves.
More holders sell the stablecoin.
Market liquidity becomes thinner.
The price falls farther below $1.
Arbitrage becomes harder or slower.
Redemptions accelerate.
Confidence falls further.
This is sometimes described as a run dynamic.
The exact mechanism differs between stablecoins, but the common feature is that confidence and liquidity can reinforce each other.
Stablecoin Depegging: Temporary vs Structural
Not every depeg has the same significance.
Temporary Depeg
The token briefly moves away from $1 due to market volatility, liquidity imbalance, or a short-lived operational issue and subsequently returns toward the target.
Persistent Depeg
The token remains materially below its target for an extended period because the underlying mechanism cannot restore the peg effectively.
Structural Failure
The stablecoin’s reserve, collateral, smart contracts, redemption mechanism, or economic design can no longer support the intended target.
This distinction is important when analyzing market events.
A token trading at $0.997 for several minutes is fundamentally different from a stablecoin trading at $0.40 because a protocol no longer has sufficient backing.
How to Monitor Stablecoin Depegging
A useful monitoring framework includes:
Price: How far is the token from $1?
Duration: How long has the deviation lasted?
Liquidity: How deep are the major markets?
Redemptions: Are holders redeeming unusually quickly?
Reserves: Are reserve assets adequate and transparent?
Collateral: Is collateral falling in value?
Exchange flows: Are large balances moving toward trading venues?
Smart contracts: Are there unusual minting or redemption events?
Oracles: Are price feeds functioning normally?
Issuer operations: Are banking or redemption channels working?
Regional markets: Is the deviation global or limited to one venue?
For broader crypto risk education, Coin Network’sCryptopedia resources can be combined with itsDeFi coverage when researching collateral, liquidity, and protocol mechanics.
Common Mistakes When Analyzing Stablecoin Depegging
Treating Every Deviation as a Collapse
Small temporary movements can occur because stablecoins trade on fragmented markets.
Looking Only at Price
A price chart does not explain why the deviation occurred.
Ignoring Redemption Access
A stablecoin can appear liquid on exchanges while its underlying redemption mechanism is impaired.
Assuming All Stablecoins Have the Same Risk
Fiat-backed, crypto-backed, and algorithmic designs have different failure modes.
Ignoring Local Markets
A stablecoin can trade above or below $1 in one country while remaining close to its target globally.
Assuming Reserves Equal Instant Liquidity
Reserve quality matters, but the composition, custody, availability, and redemption process also affect how quickly backing can support the peg.
Stablecoin Depegging: Practical Checklist
Before judging a potential depeg, check:
Price: How large is the deviation?
Duration: Is it minutes, hours, or days?
Volume: Is trading activity unusually high?
Liquidity: Are major pools deep enough?
Reserves: What assets back the token?
Redemption: Can eligible users redeem normally?
Collateral: Has backing value fallen?
Minting: Are unexpected tokens being created?
Oracles: Are price feeds functioning?
Smart contracts: Has unusual contract activity occurred?
Exchange flows: Are holders moving large balances?
Geography: Is the premium or discount global or regional?
Conclusion
Stablecoin Depegging occurs when a dollar-pegged token moves materially away from its intended $1 reference value.
The causes can range from reserve concerns and redemption pressure to liquidity shortages, collateral losses, oracle failures, smart-contract exploits, banking disruptions, and broader market stress.
The 2026 market provides several useful examples. USDT experienced a significant premium on some Indian platforms after local supply channels were disrupted, while the Resolv USR incident demonstrated how a smart-contract exploit can create a much more severe and persistent depeg.
At the same time, the overall stablecoin market remained large, with CoinDesk Research reporting approximately $311 billion in stablecoin market capitalization at the end of August 2026.
The most important lesson is that a stablecoin’s price alone does not tell the full story.
To assess a potential depeg, researchers should examine reserves, redemption mechanisms, liquidity, collateral, smart-contract activity, market structure, and the duration of the price deviation.
The key question is not simply:
“Is the stablecoin below $1?”
It is:
“Why did the peg move, and does the mechanism exist to restore it?”
FAQs
1. What is Stablecoin Depegging?
Stablecoin Depegging occurs when a stablecoin designed to maintain a target value, such as $1, trades materially above or below that target.
2. What causes a stablecoin to depeg?
Common causes include reserve concerns, redemption pressure, low liquidity, collateral losses, smart-contract exploits, oracle problems, banking disruptions, and sudden market stress.
3. Is a stablecoin trading at $0.99 automatically failing?
No.
A short-lived deviation can result from normal market liquidity conditions. Duration, liquidity, redemption access, and the underlying cause are important.
4. Can a stablecoin trade above $1?
Yes.
Strong local demand, liquidity shortages, exchange-specific conditions, or restrictions on supply can cause a stablecoin to trade at a premium.
5. What happened to USDT in India in 2026?
In June 2026, USDT reportedly traded at a premium of more than 8.5% on some Indian crypto platforms after enforcement actions disrupted parts of the local supply pipeline. The event was primarily a regional liquidity and supply disruption rather than evidence of a global USDT reserve failure.
6. Can smart-contract exploits cause Stablecoin Depegging?
Yes.
The March 2026 Resolv USR incident demonstrated this possibility. An attacker exploited weaknesses in the minting infrastructure and created approximately 80 million unbacked tokens, causing USR to fall sharply below its target.
7. Why are stablecoin reserves important?
For reserve-backed stablecoins, reserves are part of the mechanism used to support issuance and redemption.
Reserve quality, liquidity, custody, transparency, and redemption access can all affect market confidence.
8. What is the difference between a temporary and permanent depeg?
A temporary depeg may result from a short-term liquidity or market imbalance and recover toward $1.
A persistent depeg can indicate that the stablecoin’s backing, redemption mechanism, or economic design is no longer restoring the target effectively.
9. How can I monitor a potential stablecoin depeg?
Track the token’s price across multiple venues, trading liquidity, redemption activity, reserve disclosures, collateral levels, unusual minting, exchange flows, and smart-contract events.
10. Does a larger stablecoin market cap make depegging impossible?
No.
A larger market can provide greater liquidity and adoption, but it does not eliminate reserve, redemption, liquidity, technical, or market-structure risks.
11. Which stablecoins are the largest in 2026?
USDT remains the largest stablecoin by market capitalization, while USDC is the second-largest among major dollar-backed stablecoins. September 2026 market data puts USDT near $184 billion and USDC near $75 billion in supply.
12. Where can I learn more about stablecoin and DeFi risks?
Coin Network’sCryptopedia provides broader blockchain education, while itsDeFi section covers decentralized-finance concepts related to collateral, liquidity, and protocol risk.